If you earn interest from U.S. Treasury bills, notes, bonds, or Treasury Inflation-Protected Securities (TIPS), you may be able to reduce your state income tax bill legally.
Federal law generally exempts interest from direct U.S. Treasury obligations from state and local income taxes, even though that interest remains taxable on your federal return.
The key is understanding which investments qualify, how to report Treasury interest on your state tax return, and why Treasury-focused money market funds and ETFs may require additional tax calculations.
For investors holding Treasury bills through a brokerage account, using a Treasury-focused fund, or building a short-term cash portfolio, getting this distinction right can help prevent overpaying state taxes.
You generally don’t need a special tax shelter or complicated investment strategy to avoid state income tax on qualifying Treasury interest. You need eligible U.S. Treasury investments, accurate tax records, and the correct state tax-return treatment. Treasury interest is generally still subject to federal income tax.
Tax information reviewed for the 2026 tax year. State filing rules and forms vary, so verify the requirements for your state and tax situation.
Can You Avoid State Taxes on Treasury Interest?
Yes. Interest earned on direct obligations of the U.S. government is generally exempt from state and local income taxes under federal law.
This treatment is recognized by the Internal Revenue Service (IRS) and the U.S. Department of the Treasury.
The exemption covers interest from qualifying Treasury bills, notes, bonds, and TIPS. Treasury floating-rate notes are also included.
Treasury bills generate interest through the difference between the purchase price and the amount received at maturity.
However, the exemption does not mean Treasury interest is tax-free at every level. You generally still owe federal income tax on the interest.
The legal foundation is 31 U.S.C. § 3124, which establishes the general exemption for U.S. government obligations from state and local taxation, subject to specified exceptions.
The IRS explains the tax treatment in Publication 550.
Which Treasury Investments Are Exempt From State Income Tax?
The following direct U.S. Treasury investments generally qualify for the state and local income tax exemption.
| Investment | State & Local Tax | Federal Income Tax |
|---|---|---|
| Treasury bills (T-bills) | ✓ Generally exempt | Generally taxable |
| Treasury notes | ✓ Generally exempt | Generally taxable |
| Treasury bonds | ✓ Generally exempt | Generally taxable |
| Treasury Inflation-Protected Securities (TIPS) | ✓ Generally exempt | Generally taxable |
| Treasury floating-rate notes (FRNs) | ✓ Generally exempt | Generally taxable |
| Treasury-focused ETFs | Depends on income & state rules | Generally taxable distributions |
| Treasury money market mutual funds | Depends on income & state rules | Generally taxable distributions |
The first five investments are direct Treasury obligations. The last two are pooled investment products, so their state tax treatment requires additional care.
The Treasury Department confirms the exemption for direct marketable Treasury securities on its tax forms and withholding page.
7 Ways to Avoid State Taxes on Treasury Interest Legally
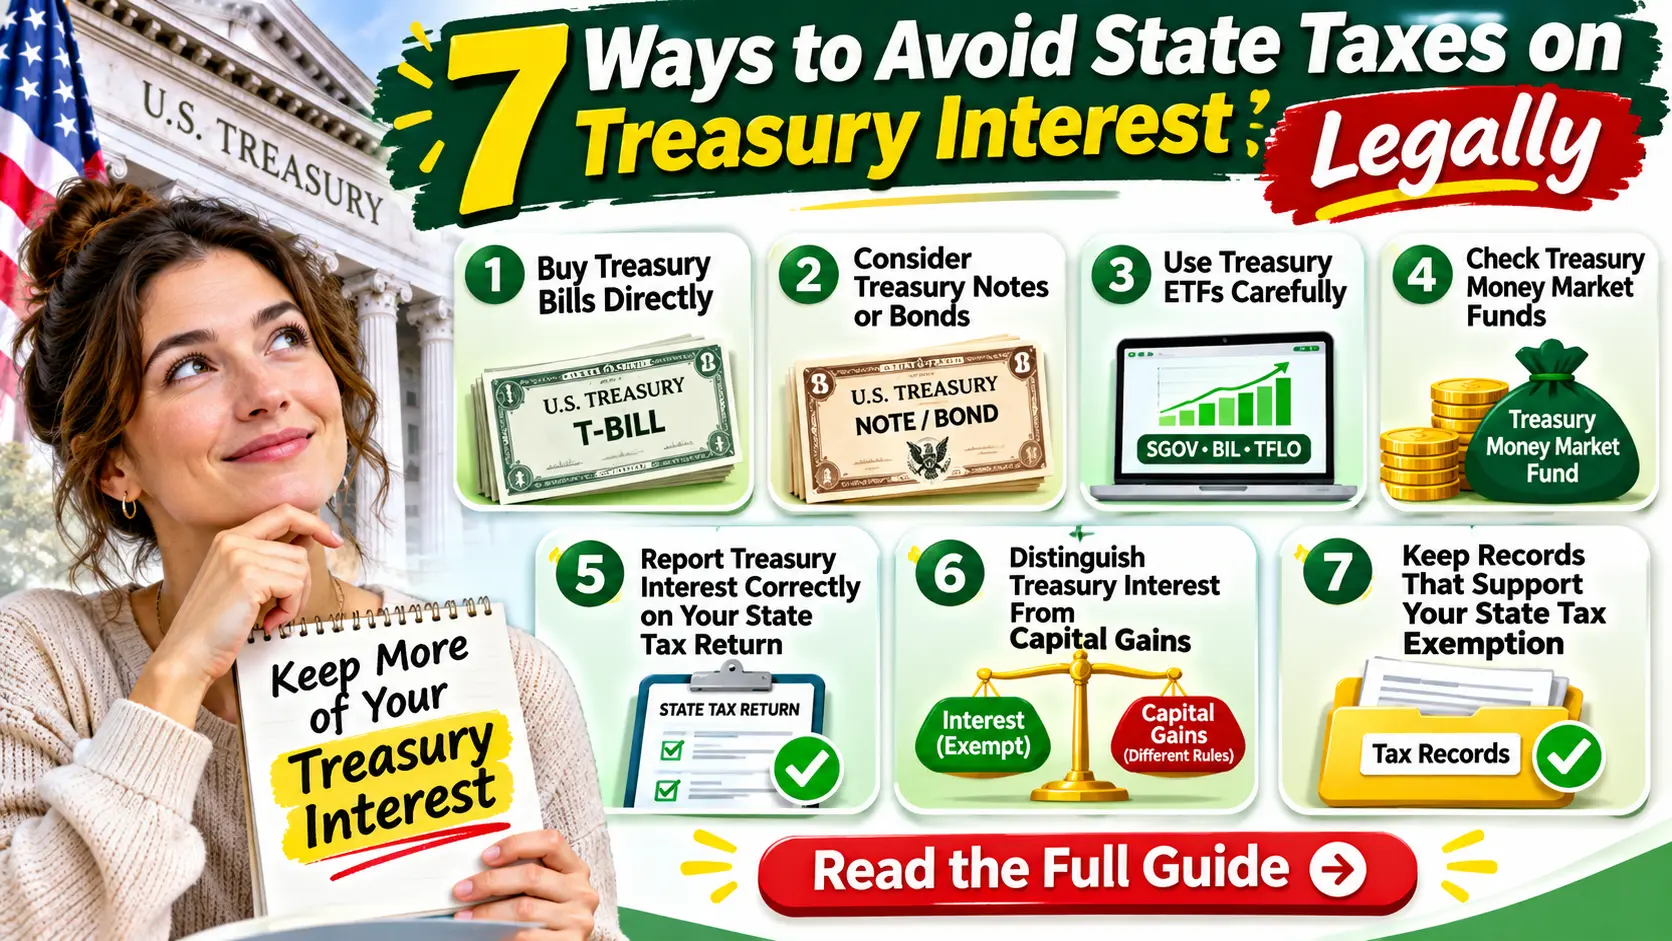
1. Buy Treasury Bills Directly
Treasury bills are short-term U.S. government securities that mature in 4, 8, 13, 17, 26, or 52 weeks, depending on the offerings available. They are typically purchased below their face value, with the difference representing interest income.
For example, suppose you purchase a Treasury bill for $9,800 and receive $10,000 at maturity. The $200 difference generally represents interest income.
If you hold the bill as a direct Treasury obligation, that interest is generally exempt from state and local income taxes, although federal income tax still applies.
You can purchase eligible Treasury bills through:
- TreasuryDirect, the U.S. Treasury’s official retail platform.
- A brokerage account that offers Treasury securities.
- A financial institution that provides access to Treasury auctions or secondary-market securities.
Best for: Investors who want a straightforward way to earn interest on cash while receiving the federal tax exemption from state and local income taxes.
One important detail: Treasury bill interest is generally reported for the year the bill matures or is sold, rather than necessarily the year you purchased it. If you reinvest the proceeds, you still need to report the interest when required.
2. Consider Treasury Notes or Bonds for Longer-Term Holdings
If you want to hold government debt for longer than a few months, Treasury notes and bonds may be appropriate alternatives to repeatedly purchasing short-term bills.
Treasury notes generally have original maturities of 2, 3, 5, 7, or 10 years. Treasury bonds generally have longer original maturities, commonly 20 or 30 years.
Their interest payments are generally exempt from state and local income taxes but remain subject to federal income tax.
For example, an investor receiving $3,000 in annual interest from qualifying Treasury notes generally does not include that interest in state taxable income where the exemption applies.
Consider maturity dates, interest-rate risk, reinvestment risk, and your need for liquidity before selecting a longer-term Treasury.
3. Use Treasury ETFs Carefully
Treasury exchange-traded funds (ETFs) can provide diversified exposure to Treasury securities without requiring you to purchase and manage each security individually.
Examples include:
- iShares 0-3 Month Treasury Bond ETF (SGOV)
- SPDR Bloomberg 1-3 Month T-Bill ETF (BIL)
- iShares Treasury Floating Rate Bond ETF (TFLO)
These funds hold Treasury securities, but do not automatically assume that every dollar of an ETF distribution is exempt from state income tax.
A fund may distribute income derived from U.S. Treasury obligations alongside other income components. State rules may also specify minimum qualifying-income percentages, reporting procedures, or other requirements.
To claim an exemption correctly:
- Download the fund’s annual tax supplement or state tax information.
- Identify the percentage of distributions attributable to qualifying U.S. government obligations.
- Check your state’s rules for the applicable tax year.
- Apply the permitted adjustment to the eligible portion of the distribution.
- Keep the fund’s tax supplement and your brokerage statement with your records.
The fund’s name alone is not sufficient evidence of the amount you can exclude.
4. Check Treasury Money Market Funds Before Claiming an Exemption
Treasury money market funds are often used to hold cash while earning income from short-term government securities.
However, the term “money market fund” covers different portfolios. Some invest primarily in Treasury bills and other U.S. government obligations, while others may hold repurchase agreements, agency securities, or different money market instruments.
That difference matters for state tax purposes.
For example, if a fund reports that 90% of its relevant distributions qualify for your state’s exemption, you should not automatically exclude 100% of those distributions. You must follow the fund’s reported qualifying percentage and your state’s applicable rules.
Before filing, look for:
- The fund’s annual tax supplement.
- Its percentage of income attributable to qualifying U.S. government obligations.
- Your state’s specific instructions for exempt-interest adjustments.
- Any state-specific minimum percentage or other eligibility requirements.
This is particularly important for investors comparing Treasury funds with money market funds that hold a wider mix of securities.
5. Report Treasury Interest Correctly on Your State Tax Return
One of the most common mistakes is assuming that the exemption happens automatically.
Your brokerage may report Treasury interest on Form 1099-INT, often in Box 3 for interest on U.S. savings bonds and Treasury obligations. You generally still report the taxable interest on your federal return.
Your state return may require a subtraction, adjustment, or other disclosure to remove qualifying Treasury interest from state taxable income.
A practical filing process is:
- Collect your Form 1099-INT and any consolidated brokerage tax statements.
- Identify interest from direct Treasury obligations separately from bank interest and other investment income.
- Review your state’s current income tax instructions.
- Enter the qualifying subtraction or adjustment on the designated line, if required.
- Retain supporting documentation in case the state tax authority requests verification.
The correct form and line depend on your state. Do not copy a subtraction amount or line number from another state’s return.
6. Distinguish Treasury Interest From Capital Gains
The state tax exemption generally applies to qualifying interest income, not automatically to every profit connected with Treasury securities.
Suppose you buy a Treasury note and later sell it for more than your adjusted tax basis. The resulting gain may be treated differently from the interest paid by the note.
Similarly, a Treasury ETF may distribute income and separately generate a capital gain when you sell your shares.
Before claiming a state tax exemption, distinguish between:
- Qualifying Treasury interest.
- Capital gains or losses from selling securities.
- Premiums, discounts, and other adjustments that may affect taxable income.
- Distributions from funds and ETFs.
The federal tax rules and your state’s rules for gains and losses should be reviewed separately. Do not assume that a gain from selling a Treasury security is automatically exempt simply because the security’s interest is exempt.
7. Keep Records That Support Your State Tax Exemption
Good records make it easier to claim the exemption accurately and respond to questions from a state tax authority.
Keep copies of:
- Forms 1099-INT and relevant brokerage tax statements.
- Treasury purchase, maturity, and sale confirmations.
- Annual ETF and mutual fund tax supplements.
- Your calculations of qualifying Treasury income.
- State tax instructions and the return filed for the applicable year.
If you own both individual Treasury securities and Treasury-focused funds, maintain separate records for each category. Direct Treasury interest is generally easier to identify, while pooled investments may require additional calculations.
How Much Can You Save on State Taxes?
Your potential savings depend on the amount of qualifying Treasury interest and your applicable state income tax rate.
Use this simple formula:
Potential state tax savings = Qualifying Treasury interest × Applicable marginal state income tax rate
For example, assume you earn $10,000 in qualifying Treasury interest and your marginal state income tax rate is 5%.
| Calculation | Amount |
|---|---|
| Qualifying Treasury interest | $10,000 |
| Illustrative state tax rate | 5% |
| Potential state tax savings | $500 |
| Federal tax treatment | Interest generally remains taxable |
This is an illustration, not a prediction of your actual tax savings. Your effective tax savings may differ depending on state law, your taxable income, deductions, and other circumstances.
Estimate Your Potential State Tax Savings
Enter your annual qualifying Treasury interest and your marginal state income tax rate to estimate the amount of state income tax that the exemption could save.
Treasury Interest Tax Calculator
Estimate how much state income tax you could save on qualifying U.S. Treasury interest.
Potential savings from the state tax exemption
Does Your State Tax Treasury Interest?
For qualifying direct U.S. Treasury obligations, the federal exemption generally applies nationwide. However, the process for claiming the exemption on a state tax return differs by state.
| State Situation | What to Know |
|---|---|
| States with individual income taxes | Qualifying Treasury interest is generally exempt, subject to applicable law and filing procedures. |
| States without a broad individual income tax | There may be no individual state income tax on interest to avoid, although other taxes may apply. |
| States with specific fund-income rules | Treasury ETF and mutual fund distributions may require additional calculations and documentation. |
Even if your state generally follows the federal exemption, check the instructions for your specific tax year before filing. The treatment of direct Treasury interest and the calculation of exempt income from a pooled fund are not necessarily identical.
Treasury Interest vs. Bank Interest: Which Is Better for State Taxes?
Bank savings accounts, certificates of deposit (CDs), and many bank money market accounts generally generate interest subject to both federal and state income taxes.
Qualifying direct Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.
Consider this simplified comparison:
| Feature | Direct Treasury Securities | Bank Savings Account |
|---|---|---|
| Federal income tax | Generally applies | Generally applies |
| State income tax on interest | Generally exempt | Generally applies |
| Local income tax on interest | Generally exempt | Depends on applicable law |
| Access to funds | Depends on maturity and sale terms | Depends on account terms |
| Principal value before maturity | May fluctuate if sold early | Depends on account and deposit terms |
For investors in states with relatively high income tax rates, the state tax exemption can make Treasuries more attractive than a bank account offering a similar pretax yield.
However, compare after-tax returns, liquidity, investment risks, and any applicable deposit insurance protections before making a decision.
How to Calculate the After-Tax Yield on Treasury Securities
A useful comparison accounts for both federal and state taxes.
For a simplified example, assume:
- Treasury yield: 4.00%.
- Federal marginal tax rate: 24%.
- State marginal income tax rate: 5%.
- Bank account yield: 4.00%.
- Interest is fully taxable at both levels for the bank account.
The simplified Treasury after-tax yield would be:
4.00% × (1 − 0.24) = 3.04%
The simplified bank account after-tax yield would be:
4.00% × (1 − 0.24 − 0.05) = 2.84%
Under these assumptions, the Treasury investment produces an after-tax yield that is 0.20 percentage points higher.
These calculations are illustrative. Actual federal and state tax outcomes can differ because of progressive tax brackets, deductions, other income, investment expenses, and other rules. This comparison also assumes the same pretax yield and does not account for differences in liquidity or investment risk.
Common Mistakes to Avoid
Before filing your taxes, watch for these errors:
- Assuming Treasury interest is exempt from federal tax. The state exemption does not eliminate federal income tax.
- Treating all Treasury ETF distributions as exempt. Use the fund’s tax information and applicable state rules.
- Excluding bank interest by mistake. Interest from a bank savings account does not qualify simply because you use the account to hold cash.
- Ignoring gains from selling securities. Capital gains and interest income can receive different tax treatment.
- Failing to report interest federally. Tax-exempt status at the state level does not mean the income should be omitted from your federal return.
- Using the wrong state’s tax instructions. The filing procedure and line numbers can differ by state.
- Assuming an exemption applies to every government-related investment. Agency securities and repurchase agreements require careful review of their specific tax treatment.
Frequently Asked Questions
Is Treasury bill interest exempt from state income tax?
Generally, yes. Interest earned on direct U.S. Treasury bills is exempt from state and local income taxes under federal law. It is generally still taxable on your federal income tax return.
Do I have to report Treasury interest on my state tax return?
You may need to report it and then claim a permitted subtraction or adjustment, depending on your state’s filing instructions. Do not assume that the interest can simply be omitted from every state return.
Is Treasury interest exempt from federal income tax?
No. Interest on Treasury bills, notes, and bonds is generally subject to federal income tax, even though it is exempt from state and local income taxes.
Are SGOV and BIL exempt from state income tax?
Potentially, in whole or in part. These ETFs hold Treasury securities, but the amount of distributions eligible for a state tax exemption depends on the fund’s income reporting and your state’s rules. Consult the relevant annual tax supplement before claiming an exemption.
Are Treasury money market funds exempt from state taxes?
Some distributions may qualify, depending on the fund’s holdings, the income reported by the fund, and state requirements. Do not assume that all distributions from a Treasury money market fund are exempt.
Can I avoid state taxes on Treasury interest if I buy Treasuries through a brokerage?
Generally, yes. Purchasing a direct Treasury obligation through a brokerage does not ordinarily eliminate the state tax exemption. You must still report the income correctly and follow your state’s filing procedures.
Are Treasury bond capital gains exempt from state income tax?
Not automatically. The exemption for Treasury interest does not mean that gains from selling Treasury securities receive the same treatment. Review the applicable federal and state rules for the specific transaction.
Is Treasury interest tax-free in every state?
Qualifying direct Treasury interest is generally exempt from state and local income taxes nationwide under federal law. However, the process for reporting it and the treatment of investment-fund distributions can vary. Other taxes and exceptions may also apply.
Final Thoughts
Avoiding state taxes on Treasury interest is primarily about understanding the tax treatment of your investments and reporting qualifying income correctly.
For a straightforward approach, consider direct Treasury bills, notes, or bonds if they fit your investment goals. If you prefer Treasury ETFs or money market funds, review the annual tax supplement and verify the applicable state rules before claiming an exemption.
The goal is not to avoid reporting income. It is to claim the exemption that the law allows, keep appropriate records, and avoid paying state income tax on interest that qualifies for the exemption.
Official references for further reading:
- IRS Publication 550: Investment Income and Expenses
- IRS Topic No. 403: Interest Received
- U.S. Treasury: Tax Forms and Withholding
- 31 U.S.C. § 3124: Exemption From Taxation
Disclaimer: This article is for educational purposes only and does not constitute individualized tax, legal, or investment advice. Tax rules and filing procedures may change. Consult a qualified tax professional regarding your circumstances.
Related Posts:
- What Is FDLXX? Yield, Tax Perks & Who Should Use It
- ACA Open Enrollment 2027: Key Dates, Premium Increases, and What Lost Subsidies Mean for You
- Tax Brackets Married Filing Jointly: Rates & Calculator Guide
- How to Avoid State Taxes on Treasury Interest: A Guide for U.S. Investors
- Treasury Bills vs. CDs: Which Is Right for Short-Term Savings?



