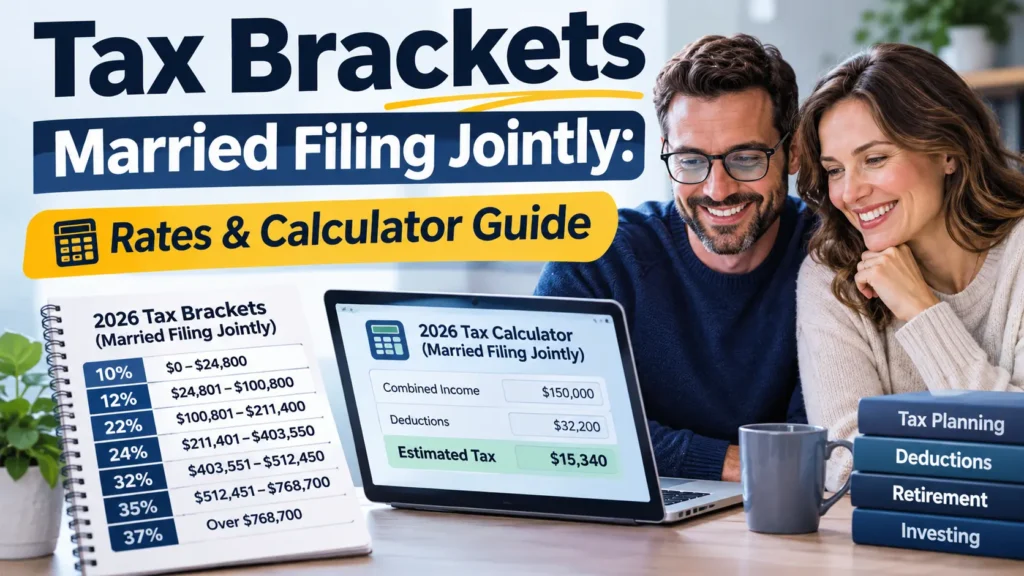
For tax year 2026, married couples filing jointly pay federal income tax at seven marginal rates: 10%, 12%, 22%, 24%, 32%, 35%, and 37%.
The 10% rate applies to the first $24,800 of taxable income, while the 37% rate applies to taxable income above $768,700.
The standard deduction for married couples filing jointly is $32,200 in 2026. Your tax bracket depends on your taxable income after eligible deductions—not simply your combined salary.
Moving into a higher bracket does not mean all your income is taxed at the higher rate.
These thresholds are for income earned during 2026, generally reported on a tax return filed in 2027.
Source: IRS 2026 tax adjustments.
Federal Tax Brackets Married Filing Jointly
The following table shows the federal income tax brackets for married couples filing jointly for the 2026 tax year.
| Federal Tax Rate | Taxable Income (2026) |
|---|---|
| 10% | $0–$24,800 |
| 12% | Over $24,800–$100,800 |
| 22% | Over $100,800–$211,400 |
| 24% | Over $211,400–$403,550 |
| 32% | Over $403,550–$512,450 |
| 35% | Over $512,450–$768,700 |
| 37% | Over $768,700 |
Important: These are marginal federal income tax rates.
Each rate applies only to the portion of your taxable income falling within that bracket.
For example, a couple with $150,000 in combined wages does not pay 22% on the entire $150,000. If they claim the $32,200 standard deduction and have no other adjustments or deductions, their taxable income is $117,800. Only the portion above $100,800 falls into the 22% bracket.
The IRS publishes the official tax rates and thresholds in Revenue Procedure 2025-32.
What Is the Standard Deduction for Married Filing Jointly in 2026?
The 2026 standard deduction for married couples filing jointly is $32,200, compared with $31,500 for tax year 2025.
The standard deduction reduces the amount of income subject to federal income tax.
You generally claim either the standard deduction or itemized deductions, depending on which option is appropriate and provides the greater deduction.
For example:
| Calculation | Amount |
|---|---|
| Combined annual income | $150,000 |
| 2026 standard deduction | −$32,200 |
| Taxable income before other adjustments or deductions | $117,800 |
This example assumes the couple’s $150,000 is their relevant income before the standard deduction and that no other adjustments or deductions apply.
Taxable income may be lower if you qualify for additional deductions.
Credits can also reduce your final tax bill, although credits work differently from deductions.
The IRS explains the 2026 standard deduction and other inflation-adjusted amounts in its official tax guidance.
How to Calculate Your 2026 Federal Income Tax
2026 Married Filing Jointly Tax Calculator
Estimate your federal income tax using the 2026 tax brackets and standard deduction.
Your estimated results
| 2026 bracket | Taxable income taxed in bracket | Estimated tax |
|---|---|---|
| 10% | $24,800 | $2,480 |
| 12% | $76,000 | $9,120 |
| 22% | $17,000 | $3,740 |
| 24% | $0 | $0 |
| 32% | $0 | $0 |
| 35% | $0 | $0 |
| 37% | $0 | $0 |
The marginal rate is the rate on your last dollar of taxable income. The effective rate shown is estimated federal income tax after entered credits divided by the income entered above; it is not your complete tax burden.
Tax year: 2026 (income generally reported on a return filed in 2027). Verify thresholds and rules with the IRS 2026 inflation-adjustment guidance.
You can estimate your federal income tax by following these steps.
- Add your household income. Include relevant wages, taxable investment income, business income, and other taxable income.
- Subtract eligible adjustments. Certain retirement contributions and other qualifying adjustments may reduce adjusted gross income, depending on the circumstances.
- Apply your deductions. Subtract the standard deduction or eligible itemized deductions, along with any other deductions you qualify for.
- Calculate tax in each bracket. Apply the relevant rate to the taxable income falling within each band.
- Subtract eligible tax credits. Credits such as qualifying child-related credits may reduce the calculated tax.
- Account for payments. Federal withholding and estimated tax payments help determine whether you owe additional tax or qualify for a refund.
Example: Married Couple Earning $150,000
Suppose a married couple has $150,000 in combined annual income, claims the $32,200 standard deduction, and has no other adjustments, deductions, or credits.
Their taxable income is:
$150,000 − $32,200 = $117,800.
Their estimated regular federal income tax is calculated as follows:
| Tax Bracket | Income Taxed at That Rate | Tax |
|---|---|---|
| 10% | $24,800 | $2,480 |
| 12% | $76,000 | $9,120 |
| 22% | $17,000 | $3,740 |
| Total | $117,800 | $15,340 |
In this simplified example, the couple’s estimated federal income tax before credits is $15,340.
Their marginal tax rate is 22%, because their last dollars of taxable income fall into the 22% bracket. Their effective federal income tax rate, measured against their $150,000 gross income, is approximately 10.2%.
This estimate excludes payroll taxes, state and local taxes, tax credits, and any other tax adjustments that may apply.
Marginal Tax Rate vs. Effective Tax Rate
Understanding the difference between these two rates helps you make better decisions about raises, bonuses, retirement contributions, and other financial choices.
Marginal tax rate: The rate applied to your next dollar of taxable income. For example, a couple in the 22% bracket generally pays 22% on additional taxable income that remains within that bracket.
Effective tax rate: Your total federal income tax divided by your gross income. It reflects the combined effect of the lower brackets and the higher brackets that apply to different portions of your income.
A couple can therefore be in the 22% marginal tax bracket while paying a much lower percentage of its total income in federal income tax.
Does a Raise Push All Your Income Into a Higher Tax Bracket?
No. The U.S. federal income tax system is progressive. When your taxable income crosses a bracket threshold, only the income above that threshold is taxed at the next marginal rate.
For instance, if your taxable income rises from $100,000 to $105,000, the amount above $100,800 falls into the 22% bracket under the 2026 married-filing-jointly thresholds. The income below that threshold continues to be taxed using the lower rates.
A raise can increase your tax bill, but crossing a bracket threshold does not automatically make all your income subject to the new rate.
2025 vs. 2026 Tax Brackets for Married Couples
The federal income tax rates remain the same for 2025 and 2026, but the income thresholds have increased. The standard deduction has also increased.
| Tax Rate | 2025 Taxable Income | 2026 Taxable Income |
|---|---|---|
| 10% | $0–$23,850 | $0–$24,800 |
| 12% | Over $23,850–$96,950 | Over $24,800–$100,800 |
| 22% | Over $96,950–$206,700 | Over $100,800–$211,400 |
| 24% | Over $206,700–$394,600 | Over $211,400–$403,550 |
| 32% | Over $394,600–$501,050 | Over $403,550–$512,450 |
| 35% | Over $501,050–$751,600 | Over $512,450–$768,700 |
| 37% | Over $751,600 | Over $768,700 |
The standard deduction increased from $31,500 in 2025 to $32,200 in 2026.
These annual adjustments help account for inflation. They can reduce the chance that inflation-related income increases alone will push taxpayers into higher brackets, although your actual outcome depends on changes in income, deductions, and other tax rules.
Which tax year should you use?
- Use the 2025 brackets when preparing a return for income earned in 2025.
- Use the 2026 brackets when estimating tax on income earned during 2026, generally reported in 2027.
Tax Brackets Married Filing Separately vs. Jointly
Married couples generally can choose to file jointly or separately, provided they meet the relevant filing requirements. The right choice depends on the household’s income, deductions, credits, state rules, and individual circumstances.
| Consideration | Married Filing Jointly | Married Filing Separately |
|---|---|---|
| Standard Deduction for 2026 | $32,200 | $16,100 |
| Income Reported | Generally combines both spouses’ income. | Each spouse generally reports their own income under applicable rules. |
| Tax Brackets | Joint income thresholds apply. | Separate-return thresholds apply. |
| Tax Credits and Deductions | May allow more favorable eligibility for certain tax benefits. | Some tax benefits may be limited or unavailable. |
| Responsibility for Tax | Both spouses can generally be held responsible for the full joint-return tax liability. | Each spouse generally has responsibility for their separate return, subject to applicable law. |
For 2026, the married-filing-separately thresholds differ from the joint thresholds. For example, the 12% bracket for separate filers extends above $12,400 through $50,400 of taxable income, while the corresponding joint bracket extends above $24,800 through $100,800.
Filing jointly often produces a lower combined federal tax bill, especially when spouses have substantially different incomes. However, filing separately can be worth examining when there are concerns about a spouse’s tax reporting, certain income-driven student loan payment arrangements, or other specific circumstances.
Do not assume that filing separately will save money simply because each spouse has a lower individual income. Compare both scenarios using the same household facts. Also consider state tax effects and the legal responsibility associated with signing a joint return.
For more details, consult the IRS’s filing status guidance.
Are There Special Tax Brackets for Married Couples Over 55?
There is no separate federal income tax bracket simply for being married and over age 55. The ordinary 2026 married-filing-jointly brackets generally apply regardless of whether either spouse is 55, 60, or 64.
Age can matter for other tax benefits, however.
For example, eligible taxpayers aged 65 or older may qualify for an additional standard deduction. For 2026, the additional standard deduction for age or blindness is generally $1,650 per qualifying condition for married individuals filing jointly, subject to the applicable rules.
Separately, legislation enacted in 2025 introduced an enhanced deduction of up to $6,000 per eligible person aged 65 or older for tax years 2025 through 2028, subject to income-based phaseouts and other requirements. This is separate from the ordinary age-related additional standard deduction.
These benefits have specific eligibility rules. Being over 55 alone does not qualify you for the age-based deductions available to eligible older taxpayers.
If you are approaching retirement, consider reviewing your retirement-account withdrawals, Social Security income, pension income, and investment income together. The way these income sources interact can affect your overall tax planning.
Check the IRS’s current guidance before claiming any age-related deduction.
What Is a Married Filing Jointly Tax Brackets Calculator?
A married filing jointly tax calculator estimates federal income tax using a couple’s combined financial information. A useful calculator should distinguish between gross income, taxable income, the marginal tax rate, and the effective tax rate.
To estimate your 2026 federal income tax, gather:
- Both spouses’ expected annual income.
- Eligible adjustments to income.
- The standard deduction or estimated itemized deductions.
- Other deductions for which you qualify.
- Applicable tax credits.
- Federal income tax already withheld or paid through estimated payments.
You can start with the IRS’s official tax resources or use a third-party calculator for a preliminary estimate. Check whether the tool includes tax credits, special deductions, state taxes, self-employment tax, and payroll taxes before relying on its final result.
For a tax return, the actual amount due or refunded depends on the full return—not just your bracket.
Frequently Asked Questions
What are the 2026 tax brackets for married filing jointly?
The 2026 federal tax brackets are 10% up to $24,800 of taxable income, 12% up to $100,800, 22% up to $211,400, 24% up to $403,550, 32% up to $512,450, 35% up to $768,700, and 37% above $768,700.
What is the standard deduction for married filing jointly in 2026?
The standard deduction is $32,200 for tax year 2026. Additional deductions may be available depending on age, blindness, income, and other eligibility requirements.
If a married couple earns $100,000, what tax bracket are they in?
If the couple earns $100,000 and claims the $32,200 standard deduction, with no other adjustments or deductions, taxable income would be $67,800. That falls in the 12% marginal bracket. Their effective tax rate would be lower than 12% because their income is taxed progressively.
Do married couples filing jointly pay less tax?
Many couples benefit from filing jointly, but not every couple will. Compare the combined tax under both filing statuses, including the impact on deductions, credits, state taxes, and any other relevant financial circumstances.
Where can I download the federal income tax tables for 2026 as a PDF?
The IRS publishes official tax forms, instructions, and tax-rate information online. Start with IRS Revenue Procedure 2025-32 for the 2026 inflation-adjusted thresholds, then check the IRS’s tax forms and instructions pages for the relevant return-year documents. Confirm that any downloaded PDF applies to tax year 2026 rather than 2025.
Are federal tax brackets the same in every state?
Yes. Federal income tax brackets are set at the federal level and do not change based on your state of residence. However, state income tax rules differ: some states have progressive brackets, some use a flat rate, and others do not impose a broad individual income tax.
Final Takeaway: Use the Right Brackets Before You Plan
The 2026 tax brackets for married filing jointly range from 10% to 37%, and the standard deduction is $32,200. The most important step is to estimate your taxable income before deciding which marginal rate applies to your household.
Use the 2026 figures for current-year planning, compare joint and separate filing if your circumstances warrant it, and review any deductions or credits you may qualify for. For a more accurate estimate, use official IRS resources or consult a qualified tax professional who can review your complete financial situation.
Next step: Gather both spouses’ income details and deductions, estimate your taxable income, and calculate the federal tax in each bracket before adjusting for credits and payments.
Related Posts:
- What Is FDLXX? Yield, Tax Perks & Who Should Use It
- ACA Open Enrollment 2027: Key Dates, Premium Increases, and What Lost Subsidies Mean for You
- Tax Brackets Married Filing Jointly: Rates & Calculator Guide
- How to Avoid State Taxes on Treasury Interest: A Guide for U.S. Investors
- Treasury Bills vs. CDs: Which Is Right for Short-Term Savings?



