Updated November 19, 2026. Figures are as of November 19, 2026 unless a date is shown. Sources: IRS releases IR-2026-133, IR-2026-135 and IR-2026-136; Revenue Procedures 2025-32 and 2026-35; Notice 2026-66; IRS publications; 26 U.S.C. The full list with dates is at the end.
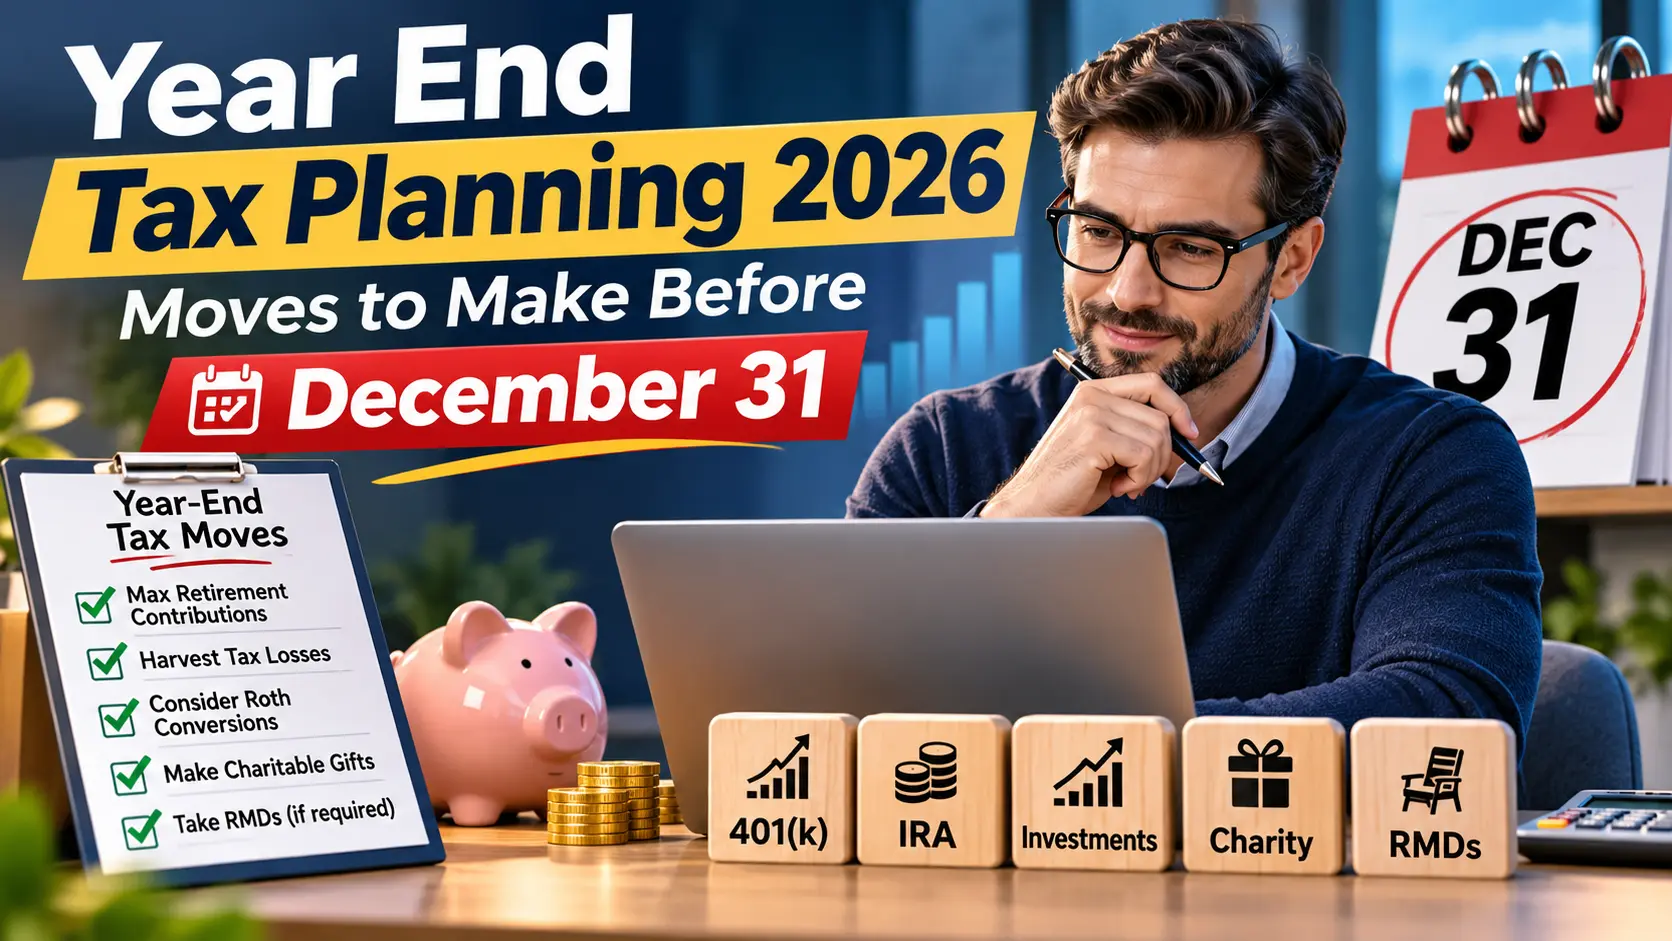
Year end tax planning for 2026 comes down to five checks: your deduction choice, retirement contributions, investment gains and losses, charitable gifts, and required withdrawals.
Most must be done by Thursday, December 31, 2026, which is six weeks from today.
Two things are new this year.
The 2025 tax law, which the IRS now calls the Working Families Tax Cuts, adds charitable-giving rules that start in 2026, including a deduction for people who do not itemize.
The IRS has also already published its 2027 limits, so you can see what comes next.
No single move fits everyone. Some save money for one household and cost another. Use this guide to learn what to ask, then confirm the details with a tax professional.
2026 Tax Deadlines & Limits: Quick Answer
Key tax dates, deductions, retirement limits, and investment rules to know before year-end.
Tax Deadlines
Most tax-saving moves must happen by December 31, 2026.
- December 31, 2026: Most year-end tax moves and RMDs.
- January 15, 2027: Fourth estimated tax payment.
- April 15, 2027: 2026 IRA contribution deadline for most taxpayers.
Standard Deduction (2026)
Here are the standard deduction amounts for the 2026 tax year:
Retirement Contribution Limits (2026)
Know how much you can contribute to your retirement accounts.
Investment & Capital Losses
Capital losses can help reduce your taxable investment gains.
- Capital losses first offset capital gains.
- Up to $3,000 of net capital losses can generally offset other income ($1,500 if married filing separately).
- Watch the IRS wash-sale rule before selling and repurchasing investments.
Required Minimum Distributions (RMDs)
If you must take a 2026 RMD, the usual deadline is December 31, 2026.
How does year-end tax planning work for 2026?
Federal income tax runs on the calendar year. Most actions that change your 2026 bill, such as selling an investment or making a Roth conversion, have to happen in 2026. A few can wait until you file.
Important Tax Deadlines to Remember
Key dates for year-end tax planning and 2026 contributions.
| DEADLINE | WHAT IT COVERS |
|---|---|
|
31
YEAR-END DEADLINE
December
Thursday, 2026
|
Complete most year-end tax moves
Finish these transactions by December 31:
ⓘ
Your employer, broker, or custodian may impose earlier processing deadlines.
|
|
15
TAX PAYMENT
January
Friday, 2027
|
Fourth estimated tax payment
Pay the fourth installment of your estimated federal income taxes for the 2026 tax year. |
|
15
CONTRIBUTION DEADLINE
April
Thursday, 2027
|
2026 IRA and HSA contributions
For most taxpayers, April 15, 2027, is the last day to make eligible contributions for the 2026 tax year to:
|
Should you itemize or take the standard deduction for 2026?
Take whichever is larger. The standard deduction is a fixed amount set by the IRS, so itemizing only helps if your qualifying expenses, such as mortgage interest, state and local taxes and charitable gifts, add up to more.
Standard Deduction: 2026 vs. 2027
Compare standard deduction amounts by federal filing status.
| Filing Status | 2026 | 2027 |
|---|---|---|
| Married Filing Jointly | $32,200 | $33,200 +$1,000 |
| Head of Household | $24,150 | $24,925 +$775 |
| Single or Married Filing Separately | $16,100 | $16,600 +$500 |
All three filing-status categories show an increase in the standard deduction compared with 2026.
Sources: IRS Rev. Proc. 2025-32 (2026 amounts) and Rev. Proc. 2026-35 (2027 amounts, released November 5, 2026). Age 65+ or blind taxpayers add $1,650 each in 2026 ($2,050 if unmarried and not a surviving spouse) and $1,700 ($2,100) in 2027.
The cap on state and local tax deductions is $40,400 for 2026 ($20,200 if married filing separately).
It shrinks when modified adjusted gross income passes $505,000 ($252,500 if married filing separately), but not below $10,000 ($5,000 if married filing separately).
That higher cap puts itemizing within reach for more households, though state tax rules differ. See how the 2026 married-filing-jointly tax brackets apply to what is left after your deduction.
New deductions you can claim without itemizing
The 2025 law added four deductions for tax years 2025 through 2028. You claim them when you file, so they are not year-end purchases.
New Tax Deductions & Income Limits
Maximum deductions and modified AGI phase-out thresholds.
| DEDUCTION TYPE | MAXIMUM AMOUNT | PHASE-OUT STARTS (MAGI) |
|---|---|---|
|
Senior Deduction
Age 65 and older
|
$6,000 Per person |
$75,000
Single / individual
$150,000 Married filing jointly
|
|
Qualified Tips
Eligible tip income
|
$25,000 Maximum deduction |
$150,000
Single / individual
$300,000 Married filing jointly
|
|
Qualified Overtime
Eligible overtime pay
|
$12,500
Single / individual
$25,000 joint
|
$150,000
Single / individual
$300,000 Married filing jointly
|
|
Car Loan Interest
Eligible vehicle loan interest
|
$10,000 Maximum deduction |
$100,000
Single / individual
$200,000 Married filing jointly
|
These are maximum deduction amounts and the income levels where phase-outs begin. Actual deductions may be reduced based on modified adjusted gross income (MAGI) and other eligibility requirements.
Source: IRS, Working Families Tax Cuts: individuals and workers, page reviewed August 27, 2026. Car loan interest applies only to loans that began after December 31, 2024, on qualifying U.S.-assembled vehicles.
How much can you put into retirement accounts before year-end?
Up to the limits below. The IRS announced the 2027 limits on November 12, 2026.
2026 vs. 2027 Retirement Contribution Limits
Compare annual workplace retirement and IRA contribution limits.
| CONTRIBUTION LIMIT | 2026 | 2027 |
|---|---|---|
| 401(k), 403(b), governmental 457 and TSP deferrals Annual employee contribution limit | $24,500 | $25,500 +$1,000 |
| Catch-up contribution Age 50 and older | $8,000 | $8,500 +$500 |
| Higher catch-up contribution Ages 60 to 63 | $11,250 | $11,750 +$500 |
| Traditional or Roth IRA Annual individual contribution limit | $7,500 | $7,500 No change |
| IRA catch-up contribution Age 50 and older | $1,100 | $1,100 No change |
The listed 401(k)-type contribution and catch-up limits increase, while the IRA limits remain unchanged in this comparison.
Sources: IRS IR-2025-111 (November 13, 2025, 2026 limits) and IR-2026-136 (November 12, 2026, 2027 limits).
Salary deferrals come out of your paychecks, so ask payroll how many pay periods are left in 2026. IRA contributions for 2026 can be made until April 15, 2027 for most people.
One new rule affects higher earners.
If your prior-year wages from the employer sponsoring the plan topped $150,000, your 2026 catch-up contributions must go in as Roth (after-tax) money.
For 2027 catch-ups, the wage threshold is $155,000 based on 2026 wages (IRS catch-up contributions page; Notice 2026-66).
Ask your plan administrator how it applies to you.
Before you raise contributions, make sure you have a cash cushion.
Our guides on how much emergency fund to keep and whether to pay off debt or save first can help you set the order.
What about a Roth conversion before December 31?
A Roth conversion moves money from a traditional IRA to a Roth IRA. Y
ou generally owe income tax on the converted amount for the year you convert it.
The IRS says a conversion made after 2017 cannot be undone, so decide before you click.
Many people check how much room is left in their bracket first.
If you also hold pre-tax IRA money, the pro-rata rule changes the tax on a backdoor Roth, as our backdoor Roth IRA guide explains.
How do you handle investment gains and losses at year-end?
Capital losses first offset capital gains.
If losses are larger, you can deduct up to $3,000 ($1,500 if married filing separately) against other income and carry the rest to later years. Gains on assets held more than one year are taxed at lower long-term rates.
Long-Term Capital Gains Tax Rates (2026)
Taxable income thresholds by federal filing status.
| FILING STATUS | 0% RATE UP TO | 15% RATE UP TO |
|---|---|---|
| Single Individual taxpayer |
$49,450
0% RATE
|
$545,500
15% RATE
|
| Married Filing Jointly Joint tax return |
$98,900
0% RATE
|
$613,700
15% RATE
|
| Head of Household Qualifying household |
$66,200
0% RATE
|
$579,600
15% RATE
|
Eligible long-term capital gains may be taxed at 0% when taxable income is within the applicable threshold.
The 15% rate generally applies to the portion of eligible gains above the 0% threshold and within the 15% bracket.
Source: IRS Rev. Proc. 2025-32 (IRB 2025-45, November 3, 2025). IRS Topic 409 (reviewed November 9, 2026) still shows the 2025 thresholds ($48,350 single, $96,700 joint); the 2026 amounts come from the Rev. Proc. For 2027 the 0% limits are $51,050 single and $102,100 joint (Rev. Proc. 2026-35).
Long-term gains above the 15% range are taxed at 20%.
A separate 3.8% net investment income tax applies when modified AGI is above $200,000 (single or head of household) or $250,000 (married filing jointly), per IRS Topic 559, reviewed September 24, 2026. The 0% range is measured by taxable income, and the gain itself counts toward that income.
Worked example: harvesting a loss (hypothetical)
This example uses made-up numbers.
Assume a single filer with 2026 taxable income of $120,000, including a $10,000 long-term gain from a fund sale.
That puts ordinary income in the 24% bracket ($105,700 to $201,750) and the gain in the 15% range.
- The filer holds another fund with a $14,000 unrealized loss and sells it in December.
- Net result: $10,000 gain minus $14,000 loss is a $4,000 net loss.
- The filer deducts $3,000 against other income and carries $1,000 to 2027.
- Federal tax avoided on the gain: $10,000 x 15% = $1,500.
- Tax saved on the $3,000 deduction: $3,000 x 24% = $720.
- Total 2026 federal saving: $1,500 + $720 = $2,220.
This is a deferral, not a free win. The replacement investment has a lower cost basis, so more gain may be taxable later. The example ignores state tax and trading costs, and your replacement may perform differently from the fund you sold.
The wash-sale rule can erase the benefit. A wash sale occurs when you sell at a loss and, within 30 days before or after, buy substantially identical securities.
That includes a purchase for your IRA or Roth IRA.
Generally the disallowed loss is added to the new shares’ cost, except when the purchase is for an IRA or Roth IRA (IRS Publication 550, 2025 edition).
State rules differ on investment income. For example, how states treat Treasury interest depends on how you hold it, as we explain in how state tax applies to Treasury interest.
How do the new charitable rules change year-end giving?
If you do not itemize, starting with tax year 2026 you can deduct up to $1,000 of cash gifts ($2,000 if married filing jointly).
Only cash counts. Gifts to supporting organizations and gifts to set up or add to a donor-advised fund do not qualify (IRS IR-2026-135, November 10, 2026).
If you itemize, 2026 brings a 0.5% floor. You can deduct only the part of your total charitable gifts that exceeds 0.5% of your contribution base, which is generally your AGI (26 U.S.C. § 170(b)(1)(I)). With a hypothetical $150,000 AGI, the first $750 of gifts does not count.
A separate rule (26 U.S.C. § 68) also trims the benefit of itemized deductions for people whose income reaches the 37% bracket.
A few timing and paperwork rules apply:
- A check you mail counts on the date you mail it, and a gift charged to a credit card counts in the year you charge it (IRS Publication 526).
- For any gift of $250 or more, keep a written acknowledgment from the charity (IRS Topic 506, reviewed November 9, 2026).
- Shares you held more than one year can be deducted at fair market value, with a 30% of AGI limit for gifts to public charities and a five-year carryover for the excess (Publication 526, reviewed April 30, 2026). Because you give the shares instead of selling them, you do not sell at a gain.
Qualified charitable distributions
If you are 70½ or older, you can send money straight from an IRA to a qualifying charity.
That amount is left out of your income, up to $111,000 per person in 2026 ($114,000 in 2027).
Donor-advised funds and supporting organizations are excluded (26 U.S.C. § 408(d)(8); IRS Notice 2026-66).
A qualified charitable distribution can also count toward your RMD (IRS Publication 590-B).
Do you have to take a required minimum distribution by December 31?
The IRS says RMDs generally begin at age 73. You can delay your first one until April 1 of the following year, but that means two distributions in one tax year. After that, each year’s RMD is due by December 31.
The penalty is a 25% excise tax on the amount you should have taken, or 10% if you correct it within two years.
On a missed $10,000 RMD (hypothetical), that is $2,500 or $1,000. The IRS may waive the penalty for a reasonable error if you file Form 5329 with an explanation (IRS retirement topics page, reviewed April 8, 2026; IRS RMD FAQs, reviewed January 29, 2026).
What about HSAs, FSAs and your withholding?
HSAs. The 2026 limit is $4,400 for self-only coverage and $8,750 for family coverage, plus $1,000 if you are 55 or older. For 2027 it is $4,500 and $9,000 (IRS Rev. Proc. 2025-19 and Rev. Proc. 2026-24). You need a qualifying high-deductible health plan. IRS Publication 969 shows April 15, 2026 as the deadline for 2025 contributions, so April 15, 2027 is the expected date for 2026.
Health FSAs. The 2026 limit is $3,400, with a $680 maximum carryover if your plan allows it. For 2027 those figures are $3,500 and $700 (IRS Rev. Proc. 2025-32 and Rev. Proc. 2026-35). Plans set their own rules, and unused money may be forfeited, so check your plan’s deadline now.
Withholding. To avoid an underpayment penalty, you generally must pay the smaller of 90% of your 2026 tax or 100% of your 2025 tax. The prior-year share rises to 110% if your 2025 AGI was above $150,000 ($75,000 if married filing separately).
Withholding is treated as paid evenly through the year unless you choose to use the actual dates, so a new Form W-4 late in the year can still help.
You can skip the January 15, 2027 payment if you file by January 31, 2027 and pay in full (IRS Publication 505, 2026 edition). The IRS Tax Withholding Estimator can help employees check their numbers.
What to do next: a seven-step checklist
Get Your Taxes Ready Before Year-End
Complete these seven important steps before December 31 to stay on top of your tax planning.
Check each task when you have completed it.
FAQs
What is the deadline for year-end tax planning in 2026?
Most moves, including Roth conversions, investment sales, charitable gifts and RMDs, must happen by Thursday, December 31, 2026. IRA contributions for 2026 can wait until April 15, 2027 for most people. The fourth estimated tax payment is due January 15, 2027.
Can I still contribute to my 401(k) for 2026 after December 31?
Salary deferrals come out of your paychecks, so check with your payroll department about the cutoff. Your plan’s rules decide when contributions count. IRA contributions are different and can be made until April 15, 2027 for most people.
How much can I deduct for charity without itemizing in 2026?
Up to $1,000, or $2,000 if you are married filing jointly. Only cash gifts to qualifying charities count. Gifts to donor-advised funds and supporting organizations do not.
Does tax-loss harvesting still work in 2026?
Yes. Losses offset gains, then up to $3,000 of other income, and any extra carries forward. The wash-sale rule can disallow a loss if you buy a substantially identical investment within 30 days before or after the sale, including in an IRA.
Can I undo a Roth conversion?
No. The IRS says conversions made in tax years beginning after December 31, 2017 cannot be recharacterized as traditional IRA contributions. A conversion is generally taxed in the year you make it.
When do I have to take my RMD for 2026?
If you took your first RMD in an earlier year, you must take the 2026 amount by December 31, 2026. If 2026 is your first year, you can wait until April 1, 2027. A missed RMD triggers a 25% excise tax, or 10% if corrected within two years.
How do I avoid an underpayment penalty for 2026?
Pay the smaller of 90% of your 2026 tax or 100% of your 2025 tax through withholding and estimated payments. Use 110% of your 2025 tax if your 2025 AGI was above $150,000. Adjusting your W-4 late in the year can still help because withholding counts as paid evenly.
The bottom line
Year-end tax planning in 2026 is mostly about timing: what you do before December 31, what can wait until April, and what the new charitable rules change for your gifts. Start with your deduction choice and your withholding, then look at retirement contributions, investment losses and RMDs. Taxes depend on your details, so confirm your plan with a tax professional before you act.
Sources
- IRS IR-2026-133, tax inflation adjustments for tax year 2027, November 5, 2026.
- IRS Rev. Proc. 2026-35, released November 5, 2026.
- IRS Rev. Proc. 2025-32, IRB 2025-45, November 3, 2025.
- IRS IR-2026-136, 401(k) limit increases to $25,500 for 2027, November 12, 2026.
- IRS Notice 2026-66, 2027 retirement plan and IRA amounts, released November 12, 2026.
- IRS IR-2025-111, 401(k) limit increases to $24,500 for 2026, November 13, 2025.
- IRS IR-2026-135, charitable contribution deduction for taxpayers who do not itemize, November 10, 2026.
- IRS, Working Families Tax Cuts: individuals and workers, reviewed August 27, 2026.
- IRS Publication 505, Tax Withholding and Estimated Tax, 2026 edition, accessed November 19, 2026.
- IRS Topic No. 409, Capital gains and losses, reviewed November 9, 2026.
- IRS Topic No. 559, Net investment income tax, reviewed September 24, 2026.
- IRS Publication 550, Investment Income and Expenses, 2025 edition.
- IRS Topic No. 506, Charitable contributions, reviewed November 9, 2026.
- IRS Publication 526, Charitable Contributions, 2025 edition, reviewed April 30, 2026.
- IRS Publication 590-B, Distributions from IRAs, 2025 edition.
- IRS Publication 590-A, Contributions to IRAs, 2025 edition, reviewed April 30, 2026.
- IRS, Retirement topics: required minimum distributions, reviewed April 8, 2026.
This article is for general education and is not personalized financial, tax, or legal advice. Tax limits, deadlines and rules change, and state rules differ, so confirm current figures with the IRS or a tax professional before you act. See our Financial Disclaimer.
Related Posts:
- Year End Tax Planning 2026: Moves to Make Before December 31
- State Tax on Money Market Funds and Treasury ETFs: Which Ones Are Exempt?
- 2027 401(k) and IRA Contribution Limits: What the IRS Announced
- VMFXX vs. SWVXX: Vanguard vs. Schwab Money Market Fund Compared
- Best High-Yield Savings Accounts for $50000: Earn Up to $2,200 a Year (November 2026)