
For high-net-worth investors, frequent international travelers, and digital nomads, traditional checking accounts paying $0.01\%$ APY while imposing foreign transaction fees and ATM surcharges are completely obsolete.
To solve this, two non-bank financial products dominate the market:
- Fidelity Cash Management Account (CMA)
- Charles Schwab Bank High Yield Investor Checking
While both accounts eliminate international ATM fees and foreign transaction surcharges worldwide, they operate under fundamentally different banking mechanics, cash sweep yields, and wire fee structures.
This comprehensive guide breaks down the feature matrices, auto-sweep yield math, travel mechanics, and internal banking architecture to help you decide which account belongs in your wallet.
1. Executive Feature Comparison Matrix
| Feature | Fidelity Cash Management Account (CMA) | Schwab High Yield Investor Checking |
| Account Structure | Non-Bank Brokerage Cash Management Account | True FDIC Bank Account (Schwab Bank) |
| Linked Account Requirement | None (Operates as a standalone account) | Requires a linked Schwab One Brokerage Account ($0 fee) |
| Primary Cash Core Yield | ~3.30% – 4.00%+ APY (Auto-sweeps to SPAXX) | ~0.45% APY (Sits in Schwab Bank default cash) |
| Auto-Sweep Mechanism | Automated (Money market funds yield automatically) | Manual (Requires purchasing SWVXX mutual fund) |
| Worldwide ATM Fee Rebates | Unlimited (Reimbursed same-day / 1 business day) | Unlimited (Reimbursed at monthly statement close) |
| Foreign Transaction Fees | 0% | 0% |
| Domestic Wire Transfers | Free ($0 outgoing wire fee) | $15 – $25 per outgoing wire |
| Deposit Insurance | Up to $5 Million via FDIC Partner Sweep or SIPC | Up to $250,000 FDIC Insurance per depositor |
| Checkbooks & Bill Pay | Free standard checks & online bill pay | Free standard checks & online bill pay |
2. The Core Yield Battle: SPAXX Auto-Sweep vs. Schwab Bank Cash Drag
The most significant operational difference between Fidelity CMA and Schwab Investor Checking lies in how uninvested cash earns interest.
Fidelity CMA: The SPAXX Core Position Revolution
Historically, Fidelity CMA cash was deposited into an FDIC-insured sweep account paying standard bank yields.
Fidelity updated its CMA functionality, allowing account holders to select the Fidelity Government Money Market Fund (SPAXX) as their default core position.
- Frictionless Auto-Liquidation: When you deposit money into a Fidelity CMA set to SPAXX, your cash automatically earns a market yield (~3.30%–4.00%+).
When you write a check, swipe your debit card, or send an electronic payment, Fidelity automatically liquidates SPAXX shares in the exact amount needed to cover the transaction. - Zero Cash Drag: You never need to manually buy or sell money market funds to earn top-tier liquid interest.
Schwab Investor Checking: The Default Low-Yield Drag
Schwab Investor Checking operates as a traditional bank account under Charles Schwab Bank, SSB. Uninvested cash sitting in the checking account earns a negligible default yield (~0.45% APY).
- Manual Sweep Friction: To earn market yield at Schwab, you must manually transfer uninvested cash from your checking account into Schwab’s Value Advantage Money Fund (SWVXX).
- Settlement Delays ($T+1$): SWVXX is a mutual fund. If you need cash to cover a large expense or debit transaction, you must sell SWVXX shares manually during market hours and wait for the trade to settle the following business day before those funds become spendable in your checking account.
The Yield Math: How Much Money Are You Leaving on the Table?
Assuming a average uninvested cash balance held over a 12-month period:
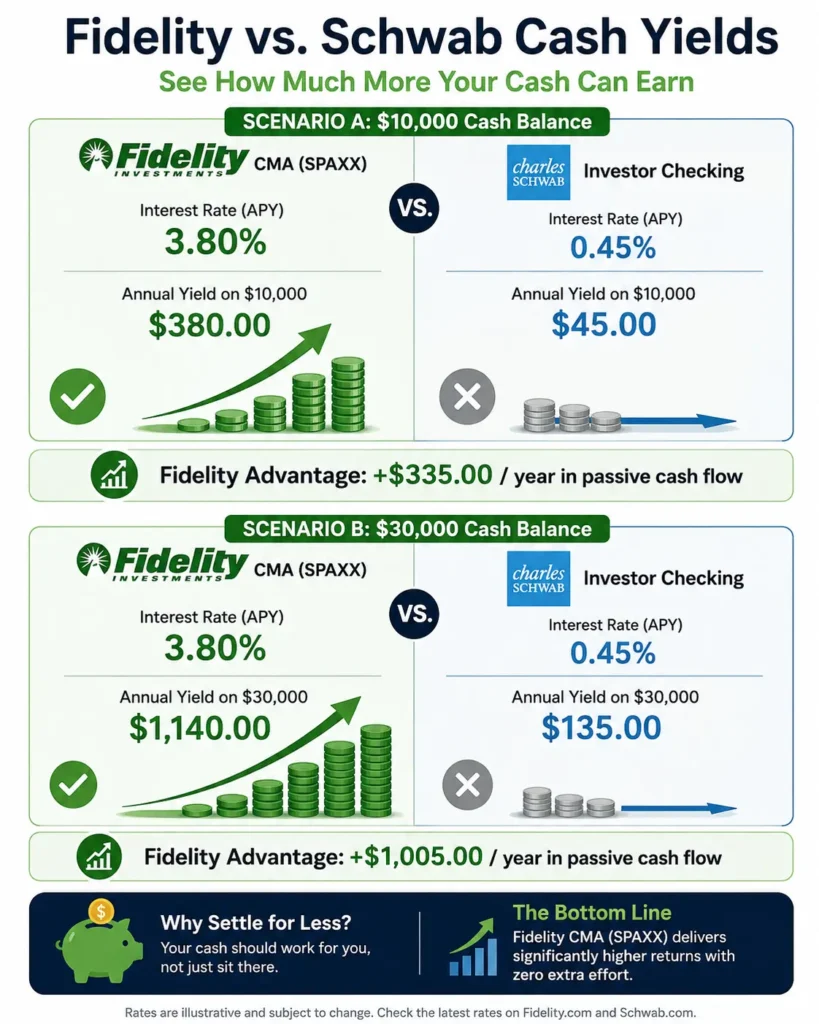
SCENARIO A: $10,000 Cash Balance
• Fidelity CMA (SPAXX @ 3.80% APY):   $380.00 Annual Yield
• Schwab Investor Checking (0.45% APY):  $45.00 Annual Yield
---------------------------------------------------------------
Fidelity Advantage: +$335.00 / year in passive cash flow

SCENARIO B: $30,000 Cash Balance (Emergency Fund + Operating Cash)
• Fidelity CMA (SPAXX @ 3.80% APY): $1,140.00 Annual Yield
• Schwab Investor Checking (0.45% APY): $135.00 Annual Yield
---------------------------------------------------------------
Fidelity Advantage: +$1,005.00 / year in passive cash flow
Takeaway:
Holding $30,000 in operational cash inside Schwab Investor Checking without manually managing SWVXX mutual fund trades results in over $1,000 per year in uncaptured yield compared to Fidelity CMA.
3. International Travel & ATM Fee Reimbursement Face-Off
Both Fidelity and Schwab are world-renowned among international travelers because both eliminate the predatory fees associated with foreign currency conversion and international bank ATMs.
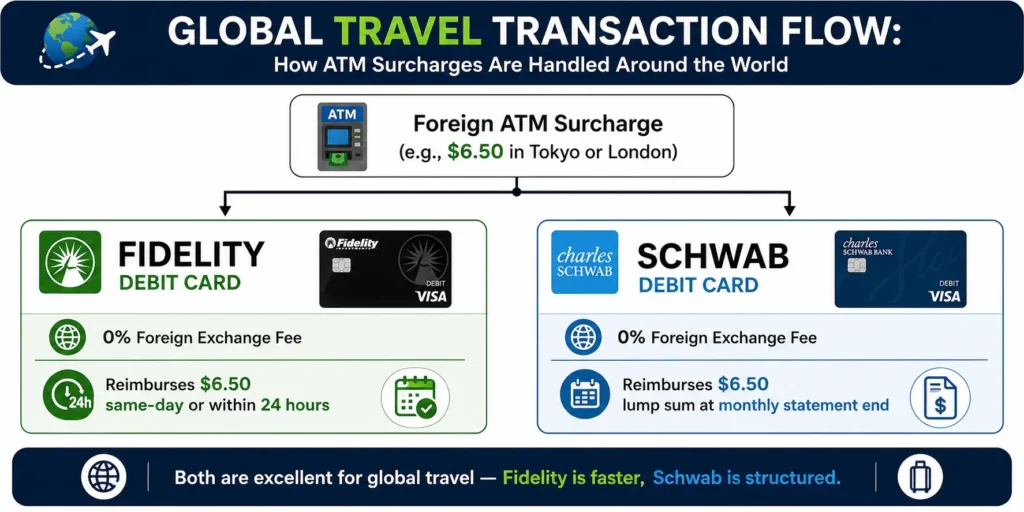
GLOBAL TRAVEL TRANSACTION FLOW:
┌────────────────────────────────────────────────────────┐
│ Foreign ATM Surcharge (e.g., $6.50 in Tokyo or London) │
└───────────────────────────┬────────────────────────────┘
                            │
            ┌───────────────┴───────────────┐
            ▼                               ▼
  FIDELITY DEBIT CARD              SCHWAB DEBIT CARD
  • 0% Foreign Exchange Fee        • 0% Foreign Exchange Fee
  • Reimburses $6.50 same-day      • Reimburses $6.50 lump sum
    or within 24 hours               at monthly statement end
Fidelity Debit Card Travel Mechanics
- ATM Fee Reimbursements: Reimburses 100% of out-of-network ATM fees charged by third-party banks worldwide. Reimbursements generally credit back to your account the same day or within 1 business day of the transaction posting.
- Foreign Exchange Fee: 0%. Fidelity does not charge a foreign transaction markup on debit card purchases or ATM withdrawals abroad.
- Currency Conversion Rate: Conversions are executed at Visa’s wholesale interbank exchange rate without retail bank markups.
Schwab Visa Platinum Debit Card Travel Mechanics
- ATM Fee Reimbursements: Reimburses 100% of out-of-network ATM fees globally with no caps.
- Reimbursement Timing: Unlike Fidelity’s near-instant reimbursement, Schwab accumulates all foreign and domestic ATM fees incurred during your billing cycle and rebates them in a single lump sum credit on the last day of your monthly statement period.
- Foreign Exchange Fee: 0%. Schwab levies no foreign transaction fees or currency conversion surcharges.
4. Banking Infrastructure, Insurance, & Wire Mechanics
Beyond cash yields and travel benefits, day-to-day administrative features differ significantly between the two accounts.
Deposit Insurance: $5M FDIC Sweep vs. Traditional Bank FDIC
- Fidelity CMA Insurance Structure: Because Fidelity is a brokerage rather than a commercial bank, uninvested cash placed in the FDIC Deposit Sweep option is spread across participating program banks, providing up to $5,000,000 in FDIC coverage. If held in SPAXX, cash is protected under SIPC insurance up to $500,000 (including $250,000 for cash claims) plus private excess-SIPC coverage.
- Schwab Checking Insurance Structure: As a charter bank, Schwab Investor Checking provides standard $250,000 FDIC insurance per depositor.
Bank Wires: A Major Perk for High Earners & Real Estate Buyers
- Fidelity CMA: Offers $0 domestic wire transfers (both incoming and outgoing). This is a major advantage when wiring home earnest money deposits, private equity investments, or moving capital between institutions on short notice.
- Schwab Investor Checking: Charges $15 to $25 per outgoing wire transfer, unless you hold top-tier high-net-worth status across Schwab accounts.
5. Which Account Should You Choose?
Choose Fidelity Cash Management Account (CMA) if:
- You want automated high-yield earnings (~3.30%–4.00%+ APY) on your everyday operational cash without doing manual mutual fund trades.
- You send frequent domestic wire transfers and want to avoid $15–$25 bank fees.
- You prefer same-day or 24-hour ATM fee rebates while traveling rather than waiting for an end-of-month statement credit.
- You want a standalone cash account without needing to open an accompanying brokerage account.
Choose Schwab Investor Checking if:
- You prefer the structural familiarity of a true FDIC-insured charter bank account attached to an established banking entity.
- You already use Schwab as your primary investment hub for active trading, options, or Thinkorswim.
- You do not mind holding a low cash balance in checking while manually managing investment capital in money market funds.
6. The Dual-Account Hybrid Strategy
Many high-net-worth investors avoid choosing between the two by using a Dual-Account Financial System:
- Fidelity CMA as the Primary Wealth & Spending Hub: Direct deposit your paycheck into Fidelity CMA with SPAXX selected as the core position. Use this account to auto-earn market yield on all uninvested cash, pay monthly bills, and execute free bank wires.
- Schwab Investor Checking as the Dedicated International Travel Card: Keep a secondary $1,000 buffer inside Schwab Investor Checking. Carry the Schwab Visa Debit Card in your travel wallet as an elite, zero-fee secondary backup card when navigating international ATMs.
Frequently Asked Questions (FAQ)
Is Fidelity CMA considered a real checking account?
Fidelity CMA is a non-bank brokerage cash management account designed to replicate all standard checking functions. It includes a debit card, routing and account numbers for direct deposit, mobile check deposit, and automated online bill pay, backed by partner bank FDIC sweep coverage or SIPC money market protection.
Does Fidelity charge foreign transaction fees on international debit card purchases?
No. Fidelity does not charge foreign transaction fees on the Fidelity Debit Card linked to a Cash Management Account. Transactions made in foreign currencies are processed using Visa’s wholesale exchange rate.
Does Schwab require a minimum balance for unlimited ATM fee rebates?
No. Schwab High Yield Investor Checking has $0 minimum balance requirements and $0 monthly maintenance fees, while still providing unlimited worldwide ATM fee rebates.