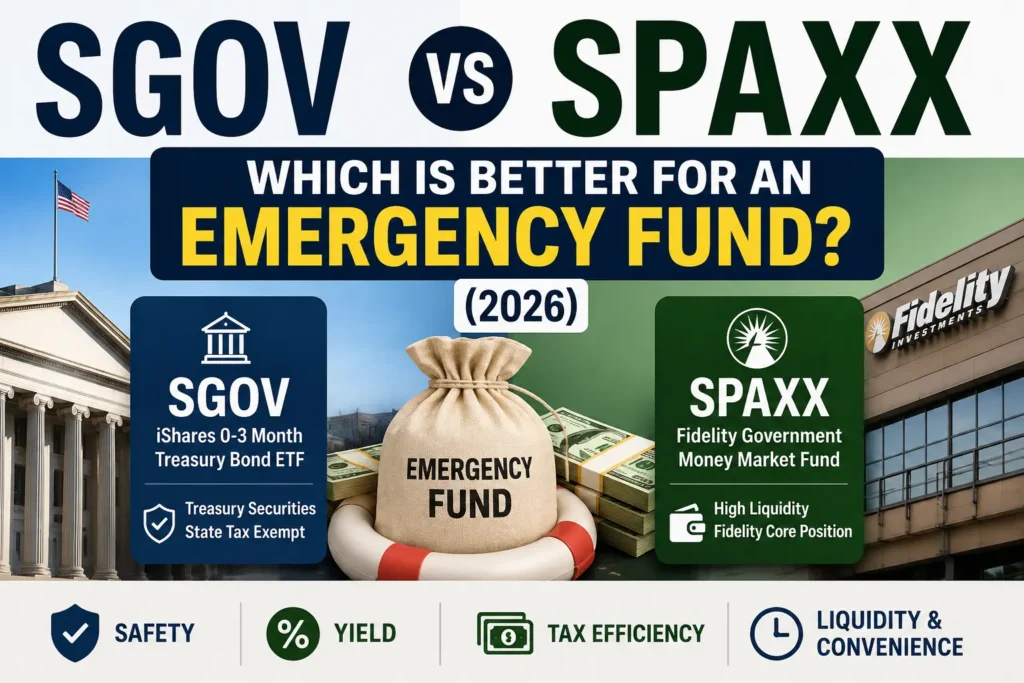
SGOV vs SPAXX: Quick Answer
If you are deciding between SGOV and SPAXX for an emergency fund, both can be strong options for keeping cash productive without taking stock-market-level risk.
The better choice depends on what you value most.
Choose SPAXX if convenience and immediate cash management are your priorities. It can serve as a Fidelity core position, so uninvested cash can automatically sit in the fund and be used for trades, withdrawals, transfers, and other account transactions.
Choose SGOV if state and local tax efficiency are more important. SGOV invests in very short-term U.S. Treasury securities, whose income is generally exempt from state and local income taxes. That can make SGOV especially attractive for investors living in states with high income-tax rates.
As of late July 2026, SGOV had a 3.57% 30-day SEC yield and a 0.09% expense ratio, while SPAXX had a 3.31% 7-day yield and a 0.42% expense ratio. These yield measurements use different methodologies and periods, so they should not be treated as a perfect apples-to-apples comparison.
For many Fidelity investors, my practical verdict is:
SPAXX wins for convenience. SGOV wins for state-tax efficiency.
SGOV vs SPAXX: Head-to-Head Comparison
| Feature | SGOV | SPAXX |
|---|---|---|
| Full name | iShares 0-3 Month Treasury Bond ETF | Fidelity Government Money Market Fund |
| Structure | ETF | Money market mutual fund |
| Main holdings | U.S. Treasury bills | U.S. government securities, agency securities, and government repos |
| Latest verified yield | 3.57% 30-day SEC yield | 3.31% 7-day yield |
| Expense ratio | 0.09% | 0.42% |
| State/local tax treatment | Generally exempt for Treasury income | Only the qualifying government-security portion may receive state/local exemption |
| Federal tax | Taxable | Taxable |
| Price | Trades throughout the day | Designed to maintain $1.00 NAV |
| Distribution | Monthly | Dividends generally paid monthly |
| Trading | Exchange-traded | Mutual fund |
| Settlement | Generally T+1 | Fidelity money market funds settle same day |
| Fidelity core position | No | Yes, in eligible Fidelity accounts |
| Automatic cash management | No | Yes when used as a core position |
| Best for | Tax-efficient short-term Treasury exposure | Simple, automated Fidelity cash management |
SGOV’s official iShares data showed a 3.57% 30-day SEC yield and a 0.09% expense ratio as of July 24, 2026. Its portfolio is focused on Treasury bills with maturities of three months or less.
Fidelity reported a 3.31% 7-day yield for SPAXX as of July 27, 2026, with a 0.42% expense ratio. SPAXX normally invests at least 99.5% of assets in cash, U.S. government securities, and fully collateralized repurchase agreements.
Related: SPAXX vs. SGOV vs. HYSA: Where to Park Emergency Cash
What Is SGOV?
SGOV is the iShares 0-3 Month Treasury Bond ETF.
It is designed to track an index of U.S. Treasury securities with remaining maturities of three months or less. Because it focuses on very short-term Treasury bills, its interest-rate sensitivity is relatively low compared with longer-duration bond funds.
SGOV trades on an exchange like a stock.
That means you buy and sell shares during market hours.
It also distributes income monthly.
For an emergency fund, SGOV is attractive because the underlying securities are short-term Treasury bills rather than corporate bonds or stocks.
Treasury securities are obligations of the U.S. government and are generally considered among the safest investments. Treasury income may also be exempt from state and local income taxes, although it remains subject to federal income tax.
SGOV’s biggest advantages
- Very short-term Treasury exposure
- Low 0.09% expense ratio
- State and local tax advantage
- Highly liquid ETF
- Monthly distributions
- Relatively low interest-rate risk
- Useful for investors who already manage their cash through a brokerage account
The major drawback is that SGOV is not a bank account or automatic cash sweep.
You must own the ETF.
If you need cash, you generally sell shares and wait for the trade to settle before the sale proceeds become fully available for withdrawal.
What Is SPAXX?
SPAXX is the Fidelity Government Money Market Fund.
Unlike SGOV, it is a mutual fund rather than an exchange-traded fund.
SPAXX invests primarily in cash, U.S. government securities, government agency securities, and repurchase agreements backed by government securities. Fidelity’s fund data shows that its portfolio included Treasury bills, Treasury coupons, agency securities, and government repurchase agreements.
SPAXX is particularly popular with Fidelity customers because it can function as a core position in eligible accounts.
Think of a core position as the cash wallet inside your Fidelity account.
Money can automatically flow into the core position when you deposit cash. When you make purchases or withdrawals, Fidelity uses the core position to process those transactions.
Fidelity explains that the core position is used for transactions such as trades, checks, electronic transfers, wire transfers, direct deposits, ATM transactions, and Bill Pay.
That makes SPAXX much more convenient than SGOV for someone who wants their emergency fund integrated with their Fidelity account.
SGOV vs SPAXX Yield: Which Pays More?
This is where you need to be careful.
The latest official figures I could verify were:
- SGOV: 3.57% 30-day SEC yield as of July 24, 2026
- SPAXX: 3.31% 7-day yield as of July 27, 2026
SGOV also has a lower expense ratio:
- SGOV: 0.09%
- SPAXX: 0.42%
At first glance, SGOV appears to have the higher yield.
But there is an important catch.
These are different yield measurements
SGOV is an ETF and reports a 30-day SEC yield.
SPAXX is a money market fund and reports a 7-day yield.
The SEC yield is a standardized measure intended to help investors compare bond funds and ETFs. The money market 7-day yield annualizes the fund’s income over a seven-day period.
Therefore, you should not conclude that SGOV will always pay more than SPAXX simply because 3.57% is higher than 3.31%.
Short-term interest rates can change.
The yields can also move at different speeds.
For an emergency fund, the bigger question is what you earn after taxes and expenses, not simply which headline yield is larger on one particular date.
SGOV vs SPAXX Expense Ratio
This is one area where the difference is straightforward.
SGOV
SGOV’s expense ratio is currently 0.09%.
SPAXX
SPAXX’s gross expense ratio is currently 0.42%.
That gives SGOV a 0.33-percentage-point expense-ratio advantage.
For every $100,000 invested, a simple comparison of the expense ratios represents roughly:
- SGOV: $90 per year
- SPAXX: $420 per year
- Difference: $330 per year
However, don’t automatically subtract those numbers from the published yields.
The published fund yields already reflect fund expenses.
The expense ratio is most useful when evaluating the underlying cost structure.
The Biggest Difference: State Income Taxes
For many investors, tax treatment is more important than the headline yield difference.
U.S. Treasury interest is generally exempt from state and local income taxes.
That means SGOV can have a significant tax advantage for investors who live in states with an income tax.
The federal government still taxes Treasury income, but states and local governments generally cannot tax interest derived from direct federal obligations.
This is one of SGOV’s biggest advantages over SPAXX.
Is SPAXX exempt from state taxes?
Not completely.
This is an important point.
SPAXX is called a Government Money Market Fund, but that does not mean 100% of its income automatically receives the same state-tax treatment as direct Treasury income.
SPAXX owns a mixture of investments.
For 2025, Fidelity reported that approximately 50.9004% of the income from the Fidelity Government Money Market Fund was earned from U.S. government securities.
That percentage is important because the portion of fund income attributable to qualifying U.S. government obligations may be eligible for state and local tax exemption, depending on the applicable state rules.
The rest may remain subject to state or local income tax.
Therefore:
SPAXX is not equivalent to owning a Treasury-only fund for state-tax purposes.
Fidelity publishes annual tax information showing the percentage of income from U.S. government securities. The exact percentage can change from year to year, so investors should check the applicable tax information for the tax year they are filing.
Example: Why State Taxes Can Change the Winner
Suppose you have a $100,000 emergency fund.
Imagine both funds generated approximately 3.5% before taxes.
That would produce about:
$3,500 of annual income.
If you live in a state with no individual income tax, the state-tax advantage of SGOV may not matter much.
But suppose your state and local marginal tax rate is 8%.
If all $3,500 of income were subject to that 8% state/local tax, the tax would be:
$280 per year.
Treasury income can generally avoid that state/local tax.
SPAXX may receive partial state-tax treatment because part of its income comes from qualifying government securities, but the entire distribution isn’t necessarily exempt.
That means the higher your state and local tax rate, the more valuable SGOV’s Treasury exposure can become.
The key takeaway
If you live in:
- California
- New York
- New Jersey
- Connecticut
- Oregon
- Minnesota
- Or another relatively high-tax state
the state-tax difference deserves serious consideration.
If you live in a state without individual income tax, the tax advantage becomes much less important.
SGOV vs SPAXX Liquidity
Both are highly liquid.
But they provide liquidity in different ways.
SGOV liquidity
SGOV trades like an ETF.
You can place a market or limit order during market hours.
If you sell SGOV, the trade generally follows the standard T+1 settlement cycle for exchange-traded securities.
That means a Monday sale generally settles Tuesday, assuming both are business days.
Fidelity lists listed equities and similar exchange-traded securities as settling one business day after the trade.
This is not necessarily a problem for an emergency fund.
But it is an extra step.
You need to sell the ETF.
Then the proceeds need to settle.
Then you can move the cash to your bank if necessary.
SPAXX Liquidity
SPAXX is much more integrated into Fidelity’s cash-management system.
Fidelity lists its own money market funds as having same-day purchase and sale settlement.
When SPAXX is your Fidelity core position, you don’t normally need to manually sell SPAXX before using the cash for an eligible Fidelity transaction.
Fidelity explains that the core position automatically processes purchases, withdrawals, transfers, and other cash transactions.
This is a major advantage for emergency funds.
Imagine your car breaks down and you need $3,000.
With SPAXX as your core position, you can use the Fidelity account’s available cash-management features without first placing an ETF sell order.
With SGOV, you generally need to sell shares first.
Winner for convenience: SPAXX
Is SPAXX Really “Instant Cash”?
There is an important distinction here.
SPAXX can provide very convenient access to cash inside Fidelity.
That does not necessarily mean money can appear in your external bank account instantly.
Fidelity’s cash-management features can support transfers, wires, debit-card spending, checks, and other transactions, but external ACH transfers can still take time.
Fidelity says its Cash Management Account provides features such as debit-card access, checkwriting, Bill Pay, direct deposit, and money transfers.
So don’t interpret “SPAXX is liquid” as:
“I can transfer unlimited money to my bank instantly at any time.”
The actual speed depends on the transaction method.
SGOV vs SPAXX Safety
Both are designed for investors seeking relatively stable short-term cash exposure.
But neither should be described as exactly the same thing as an FDIC-insured savings account.
SGOV
SGOV owns short-term U.S. Treasury securities.
Treasury securities are backed by the full faith and credit of the U.S. government.
However, SGOV itself is an ETF.
Its market price can move slightly above or below its net asset value.
That does not make it equivalent to a checking account.
SPAXX
SPAXX is a government money market mutual fund.
It is designed to maintain a $1.00 share price, but Fidelity explicitly states that money market funds are not bank accounts and are not FDIC-insured.
Fidelity also notes that SPAXX is subject to market risk and that a money market fund can potentially lose money.
SPAXX may qualify for SIPC protection when held through Fidelity, but SIPC protection is not the same thing as FDIC deposit insurance and does not protect against investment losses.
Important emergency-fund point
If FDIC insurance is your top priority, neither SGOV nor SPAXX should be treated as a direct replacement for an FDIC-insured bank deposit.
SGOV vs SPAXX: Which Is Better for a Fidelity Account?
If your emergency fund is already at Fidelity, SPAXX has a major structural advantage.
It can be used as the account’s core position in eligible Fidelity accounts.
That means your emergency fund can effectively become part of the account’s cash-management system.
You don’t need to manually manage an ETF position every time you want to use your cash.
Fidelity describes the core position as the account’s “wallet” for uninvested cash.
This simplicity is difficult to beat.
Example
Suppose you keep $20,000 for emergencies.
With SPAXX:
- Deposit the money into Fidelity.
- Cash goes into the core position.
- SPAXX generates income.
- Fidelity can automatically use the core cash for eligible transactions.
- You don’t need to manually sell an ETF when you need the money.
With SGOV:
- Deposit cash into your brokerage account.
- Buy SGOV.
- SGOV generates income through its Treasury portfolio.
- When you need money, sell SGOV.
- Wait for the ETF transaction to settle.
- Withdraw or transfer the settled cash.
Neither process is difficult.
SPAXX simply involves fewer moving parts.
SGOV vs SPAXX for Emergency Fund: Pros and Cons
SGOV Pros
- Very short-term Treasury exposure
- 0.09% expense ratio
- Strong state/local tax advantage
- High trading liquidity
- Monthly distributions
- Useful for investors in high-tax states
- Easy to hold in most brokerage accounts
SGOV Cons
- Not a core cash position
- Requires an ETF trade when you need to raise cash
- T+1 settlement
- Market price can fluctuate slightly
- Less convenient for everyday spending
- No automatic Fidelity cash sweep functionality
SPAXX Pros
- Can serve as a Fidelity core position
- Automatic cash management
- Same-day Fidelity money-market settlement
- Very convenient for withdrawals and transactions
- $1.00 NAV design
- Low-risk government money-market portfolio
- No need to manually sell an ETF for normal Fidelity transactions
SPAXX Cons
- Higher 0.42% expense ratio
- Not entirely state-tax exempt
- State-tax treatment depends on the qualifying government-income portion
- Not FDIC insured
- Yield can change with short-term interest rates
- More taxable at the state level than a Treasury-only investment for many investors
SGOV vs SPAXX: Which Should You Choose?
Here’s the simplest decision framework.
| Your situation | Better choice |
| You want maximum convenience | SPAXX |
| You use Fidelity for everyday cash | SPAXX |
| You want an automatic cash position | SPAXX |
| You live in a high-tax state | SGOV |
| You want Treasury-only exposure | SGOV |
| You prioritize state-tax efficiency | SGOV |
| You want the lower expense ratio | SGOV |
| You need to spend directly from the account | SPAXX |
| You are comfortable selling an ETF when needed | SGOV |
| You want your emergency fund integrated into Fidelity | SPAXX |
| You want short-term Treasury exposure outside Fidelity | SGOV |
When SPAXX Makes More Sense
SPAXX is probably the better choice if your main goal is:
“I want my emergency fund to earn a reasonable yield while remaining extremely easy to access.”
This is especially true if you already use Fidelity.
The convenience of having your emergency fund as the core position can outweigh a modest yield or tax difference.
You don’t want an emergency fund to become a project.
If your car needs an unexpected repair, you don’t want to think about ETF trading mechanics.
You want the money to be available.
SPAXX is excellent for that use case.
When SGOV Makes More Sense
SGOV becomes more compelling when taxes matter.
Suppose you live in a high-tax state and have a large emergency fund.
The state-tax exemption on Treasury income can potentially save more money than a small difference in headline yields.
SGOV’s 0.09% expense ratio is also significantly lower than SPAXX’s 0.42%.
For investors who already have a brokerage account and don’t mind selling an ETF when they need cash, SGOV can be an efficient way to hold short-term reserves.
Should You Keep Your Entire Emergency Fund in SGOV or SPAXX?
Not necessarily.
Your emergency fund should be designed around how quickly you might need the money, not just the highest yield.
One practical approach is to divide your emergency savings into layers.
Layer 1: Immediate cash
Keep a small amount in a checking or savings account.
This covers expenses that cannot wait.
Examples include:
- Emergency medical expenses
- Urgent home repairs
- Car repairs
- Immediate travel
- Unexpected bills
Layer 2: Short-term reserve
This is where SPAXX can be useful.
You can earn a money-market yield while keeping the funds highly accessible through Fidelity.
Layer 3: Larger reserve
For investors with a larger emergency fund, SGOV can become more attractive.
The Treasury exposure and state-tax treatment can matter more as the balance grows.
For example, someone with a $5,000 emergency fund may care more about convenience than squeezing out every possible dollar of tax savings.
Someone holding $100,000 or more in cash reserves may have a much stronger incentive to optimize taxes, expenses, and yield.
What About Using Both SGOV and SPAXX?
You don’t necessarily have to choose only one.
A combination can make sense.
For example:
Immediate emergency cash: Bank savings/checking
Next layer: SPAXX
Longer-term emergency reserve: SGOV
This creates a liquidity ladder.
You get immediate access to some money while still allowing larger reserves to earn income.
The downside is additional complexity.
If your emergency fund is relatively small, the difference may not justify managing multiple positions.
SGOV vs SPAXX: The $50,000 Example
Consider someone with a $50,000 emergency fund.
Assume, purely for illustration, a 3.5% annual yield.
$50,000 × 3.5% = $1,750 per year
Now imagine the investor lives in a state with a meaningful income tax.
If SGOV’s income qualifies for the state-tax exemption while SPAXX has only partial state-tax-exempt income, the after-tax difference could become meaningful.
But if the investor lives in Texas, Florida, Nevada, Tennessee, or another state without a broad individual state income tax, the tax advantage becomes much less important.
In that situation, SPAXX’s convenience could easily win.
This is why there is no universal answer to:
“Is SGOV better than SPAXX?”
The answer depends on your state, account type, balance, liquidity needs, and willingness to manage an ETF.
A Note About SGOV and Emergency-Fund Risk
SGOV is often described as “cash-like.”
That’s reasonable in a practical sense, but it isn’t literally cash.
It is an ETF that owns Treasury bills.
The share price can fluctuate.
It can trade at a small premium or discount to its underlying net asset value.
And you have to sell shares when you want to turn the position into cash.
Those risks are relatively small compared with stock-market investments, but they are still worth understanding.
For an emergency fund, liquidity and capital preservation should come before chasing the highest yield.
A Note About SPAXX and FDIC Insurance
SPAXX is also sometimes described as “cash.”
Again, that’s convenient shorthand.
SPAXX is an investment fund.
It isn’t a checking account.
It isn’t an FDIC-insured savings account.
Fidelity states that SPAXX is not insured or guaranteed by the FDIC or another government agency. Fidelity also explains that SIPC protection is different from protection against market losses.
If you want FDIC insurance, consider an eligible bank deposit or Fidelity’s FDIC-Insured Deposit Sweep Program instead.
Fidelity says its Cash Management Account can provide an FDIC-insured sweep option, subject to applicable limits and program rules.
SGOV vs SPAXX: Final Verdict
So, SGOV vs SPAXX — which is better for an emergency fund?
There isn’t one winner for everyone.
Choose SPAXX if:
- You already use Fidelity.
- You want automatic cash management.
- You want your emergency fund available for Fidelity transactions.
- You value convenience over tax optimization.
- You don’t want to manually sell an ETF during an emergency.
- You want a simple “set it and forget it” approach.
Choose SGOV if:
- You want short-term Treasury exposure.
- You live in a state with income tax.
- State-tax efficiency is important to you.
- You want a lower expense ratio.
- You are comfortable selling an ETF when you need cash.
- You are managing a larger cash reserve where tax differences matter more.
The Bottom Line
SPAXX is the better emergency-fund choice for convenience.
SGOV is the better choice for Treasury exposure and state-tax efficiency.
For a Fidelity investor who wants simplicity, SPAXX is hard to beat.
For an investor in a high-tax state who is comfortable managing an ETF, SGOV can produce a better after-tax result.
And for larger emergency funds, using a combination of immediate cash, SPAXX, and SGOV can create a flexible liquidity strategy.
The most important thing is not squeezing out the last 0.10% of yield.
Your emergency fund’s first job is to be there when you need it.
SGOV vs SPAXX FAQs
Is SGOV safer than SPAXX?
Both are designed around high-quality, short-term government-related investments, but they have different structures. SGOV is an ETF holding Treasury bills, while SPAXX is a government money market mutual fund. Neither is the same as an FDIC-insured bank deposit.
Is SGOV tax-free?
No. SGOV income is generally taxable at the federal level. The key tax advantage is that qualifying Treasury income is generally exempt from state and local income taxes.
Is SPAXX state-tax exempt?
Only partially in many cases. The portion of SPAXX income attributable to qualifying U.S. government securities may be eligible for state and local tax exemption. Fidelity reported 50.9004% of SPAXX’s 2025 income as earned from U.S. government securities. The percentage can change each year.
Does SGOV pay monthly?
Yes. SGOV has a monthly distribution frequency.
Does SPAXX pay monthly?
SPAXX accrues income daily and distributes dividends monthly. Fidelity’s fund information shows its yield and monthly income distribution structure.
Can I use SPAXX as an emergency fund?
Yes, many investors use SPAXX for short-term cash reserves because of its liquidity and Fidelity core-position functionality. However, SPAXX is an investment fund and is not FDIC insured.
Can I use SGOV as an emergency fund?
Yes. SGOV’s short-term Treasury holdings make it a reasonable cash-management option for investors who understand ETF trading and settlement. However, it is not a bank account and isn’t as convenient as a Fidelity core position.
Which has the higher yield, SGOV or SPAXX?
Based on the latest official figures verified for this comparison, SGOV had a 3.57% 30-day SEC yield as of July 24, 2026, while SPAXX had a 3.31% 7-day yield as of July 27, 2026. Because these are different yield measures, they should not be treated as a perfect apples-to-apples comparison.
Is SPAXX better than a high-yield savings account?
It can be, depending on the yield, taxes, insurance, and features you value. A high-yield savings account may provide FDIC insurance, while SPAXX is a money market fund and is not FDIC insured. Compare after-tax yield and access rather than looking only at the advertised rate.
Is SGOV better than a high-yield savings account?
Not necessarily. SGOV can offer Treasury exposure and state-tax advantages, but a bank savings account can offer FDIC insurance and may be easier for immediate spending. Your tax bracket, state, yield, and liquidity requirements should determine the choice.
Data Sources and Update Note
Fund yields change frequently.
For this article, the latest official figures verified were:
- SGOV: 3.57% 30-day SEC yield, 0.09% expense ratio, data dated July 24, 2026.
- SPAXX: 3.31% 7-day yield, 0.42% expense ratio, data dated July 27, 2026.
- SPAXX 2025 government-security income: 50.9004%.
Because yields and tax allocations can change, readers should verify the latest fund data and their own state’s tax rules before making an investment decision.
This article is for educational purposes only and is not individualized investment, tax, or financial advice. Consult a qualified tax or financial professional for advice based on your circumstances.