What Is Discounted Cash Flow Training?
Discounted cash flow (DCF) training teaches you how to estimate the present value of a business using its expected future cash flows. The basic process is:
- Forecast future free cash flow.
- Choose an appropriate discount rate.
- Calculate terminal value.
- Discount future cash flows to today.
- Calculate enterprise value or equity value.
- Test the model with sensitivity analysis.
DCF is widely used in investment analysis, corporate finance, equity research, mergers and acquisitions, and financial modeling.
Harvard Business School describes DCF as a way to estimate value from expected future cash flows and the time value of money.
For someone learning financial modeling, the goal is not simply to memorize a formula. Good discounted cash flow training teaches you why each assumption matters and how small changes can materially affect valuation.
Why DCF Training Matters in 2026
The economic environment makes understanding valuation assumptions especially important.
As of August 2026, U.S. consumer prices were 3.4% higher than a year earlier, while core CPI was up 2.4%.
At the same time, the Federal Reserve raised its target federal funds rate to 3.75%–4.00% on September 16, 2026 and said inflation remained elevated.
Economic growth has also moderated. The Bureau of Economic Analysis reported that real U.S. GDP grew at a 1.5% annual rate in Q2 2026, compared with 2.1% in Q1.
These conditions matter to DCF modeling because interest rates, inflation, financing costs, growth expectations, and business risk influence the assumptions used in valuation.
A higher discount rate generally reduces the present value of future cash flows. Damodaran’s valuation framework similarly emphasizes that the discount rate should reflect the riskiness of expected cash flows.
That makes DCF training particularly useful for analysts who need to understand how changing financial assumptions affects estimated business value.
What Is a Discounted Cash Flow Model?
A DCF model estimates the value of an asset or business by calculating the present value of expected future cash flows.
The underlying concept is the time value of money. A dollar received today is generally worth more than a dollar received several years from now because money available today can potentially be invested.
The general DCF relationship can be expressed as:
Present Value = Future Cash Flow ÷ (1 + Discount Rate)ⁿ
Where:
- Future Cash Flow = expected cash generated in a future period
- Discount Rate = required rate of return for the risk involved
- n = number of periods until the cash flow is received
For a business valuation, analysts normally forecast several years of cash flows and then estimate a terminal value for the period beyond the explicit forecast.
What Do You Learn in Discounted Cash Flow Training?
A complete DCF course should cover more than the basic equation.
1. Financial Statement Analysis
Before building a DCF, you need to understand the company’s income statement, balance sheet, and cash flow statement.
You should be able to identify:
- Revenue
- Operating expenses
- EBIT
- Taxes
- Capital expenditures
- Depreciation and amortization
- Working capital
- Debt and cash
CFI notes that a DCF model is commonly built on a broader three-statement financial model.
2. Free Cash Flow
One of the most important concepts in DCF training is free cash flow.
For a firm-level DCF, analysts often use unlevered free cash flow, also called free cash flow to the firm.
A simplified structure is:
UFCF = EBIT × (1 − Tax Rate) + D&A − CapEx − Change in Net Working Capital
This attempts to measure cash generated by operations after taxes and reinvestment needs, before payments to debt and equity holders.
Damodaran distinguishes between firm valuation, which uses free cash flow to the firm and a cost of capital, and equity valuation, which uses free cash flow to equity and the cost of equity.
How to Build a DCF Model Step by Step
Step 1: Forecast Revenue
Start with historical financial results.
You can use a simple growth-rate assumption for a mature company, or a driver-based approach for a more detailed model.
For example:
| Year | Revenue Growth | Revenue |
|---|---|---|
| 2026A | — | $100M |
| 2027E | 8% | $108M |
| 2028E | 7% | $115.6M |
| 2029E | 6% | $122.5M |
| 2030E | 5% | $128.6M |
The numbers above are illustrative, not a forecast for any specific U.S. company.
A strong model explains why growth changes rather than simply extending historical growth forever.
Step 2: Forecast Operating Margins
Next, estimate costs and operating profitability.
For example, you might forecast EBIT margins gradually moving from 18% to 20%.
Avoid assuming dramatic margin improvement without a business reason.
A DCF becomes less useful when assumptions are designed mainly to produce a desired valuation.
Step 3: Calculate Free Cash Flow
From operating profit, account for taxes and reinvestment.
Your model should consider:
- Operating taxes
- Depreciation
- Capital expenditures
- Changes in working capital
- Other material operating investments
CFI emphasizes the importance of modeling capital assets, CapEx, depreciation, and working capital when constructing a DCF.
Step 4: Determine the Discount Rate
The discount rate is one of the most important DCF assumptions.
For a firm-level valuation, analysts often use WACC, or weighted average cost of capital.
WACC reflects the company’s financing mix and the required return associated with its debt and equity.
For equity cash flows, analysts may instead use the cost of equity.
Harvard Business School notes that cost of equity may be estimated using CAPM, while WACC is commonly applied to free cash flow to the firm.
In 2026, this deserves careful attention because the Federal Reserve’s September 16 policy move placed the federal funds target range at 3.75%–4.00%. That does not mean a company’s WACC should simply equal the federal funds rate.
A company’s discount rate also depends on its capital structure and risk.
Step 5: Calculate Terminal Value
Your explicit forecast may cover five or ten years, but a business can continue operating after that period.
Terminal value attempts to capture the value beyond the explicit forecast.
Two commonly taught methods are:
Perpetuity Growth Method
Terminal Value = FCFₙ₊₁ ÷ (WACC − g)
Where g is the long-term growth rate.
Exit Multiple Method
Terminal Value = Final-Year EBITDA × Exit Multiple
CFI identifies both the perpetuity growth and exit multiple approaches as standard methods for terminal value.
Terminal value deserves special scrutiny because it can represent a large portion of a DCF’s total value, especially when the forecast period is relatively short.
Step 6: Discount the Cash Flows
Each forecast-year cash flow must be converted into today’s value.
The further into the future the cash flow occurs, the greater the effect of discounting.
For more precise Excel modeling, timing matters. CFI recommends functions such as XNPV and XIRR when actual dates are important rather than assuming perfectly equal periods.
Step 7: Calculate Enterprise Value
When you discount unlevered free cash flow and terminal value, the result represents an estimate of enterprise value.
A simplified calculation is:
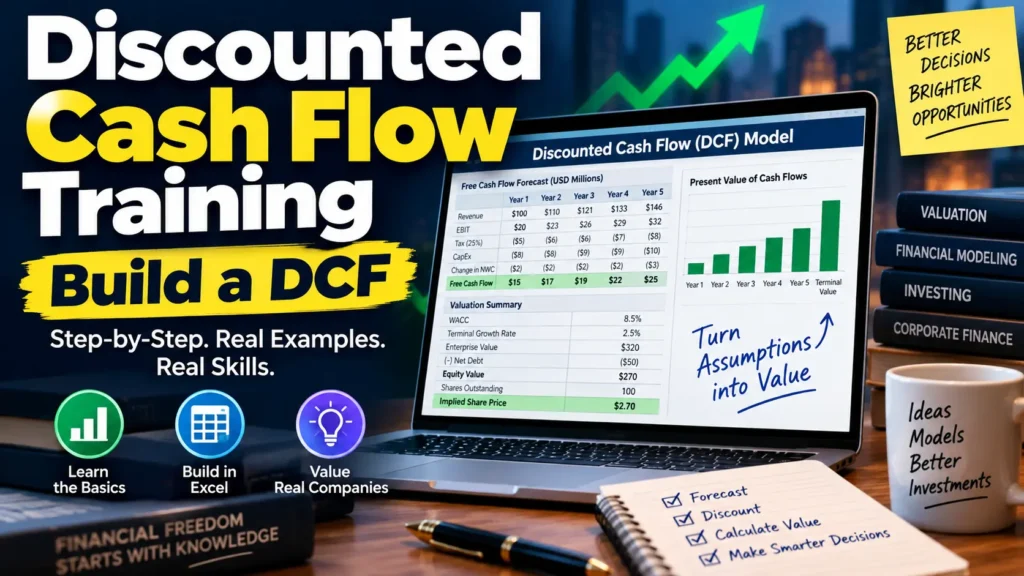
Enterprise Value = PV of Forecast FCF + PV of Terminal Value
The enterprise value represents the value of the operating business before adjusting for claims such as debt and excess cash.
Step 8: Move From Enterprise Value to Equity Value
To estimate equity value, make the appropriate balance-sheet adjustments.
A simplified framework is:
Equity Value = Enterprise Value + Cash − Debt − Other Non-Equity Claims
Then:
Value Per Share = Equity Value ÷ Diluted Shares Outstanding
Damodaran explains that moving from firm value to equity value requires considering cash, debt, and other non-equity claims.
What Is WACC in a DCF Model?
WACC stands for weighted average cost of capital.
It combines the required returns associated with the company’s debt and equity financing.
A simplified expression is:
WACC = (E/V × Cost of Equity) + (D/V × After-Tax Cost of Debt)
Where:
- E = market value of equity
- D = market value of debt
- V = total capital
- Cost of Equity = required return for shareholders
- After-Tax Cost of Debt = borrowing cost after the tax effect
The exact calculation can become much more detailed, particularly when estimating beta, the equity risk premium, debt costs, and target capital structure.
This is why quality discounted cash flow training should include WACC and CAPM, not just spreadsheet formulas.
Expert Insight: Never choose a discount rate simply because it produces a valuation you like. Your rate should have an economic and risk-based rationale that you can explain and defend.
Why Is DCF So Sensitive to Assumptions?
DCF is powerful because it connects valuation to expected cash generation.
It is also sensitive because the model depends on assumptions about the future.
Changing any of these can materially change estimated value:
- Revenue growth
- EBIT margin
- Tax rate
- Capital expenditures
- Working capital
- WACC
- Terminal growth
- Exit multiple
Harvard Business School specifically notes that DCF results can vary significantly when key assumptions change.
That is why a professional DCF should not produce only one number.
Use Sensitivity Analysis
Create a table showing how estimated value changes under different WACC and terminal-growth assumptions.
For example:
| WACC | 2% Growth | 3% Growth | 4% Growth |
|---|---|---|---|
| 8% | $X | $X | $X |
| 9% | $X | $X | $X |
| 10% | $X | $X | $X |
The figures should be calculated from your own model.
Sensitivity analysis helps you understand the range of values implied by your assumptions, rather than treating one output as an exact answer.
People Also Ask: Is DCF Hard to Learn?
DCF is easier to understand when learned in stages.
A beginner can start with:
- Time value of money
- Financial statements
- Free cash flow
- WACC
- Terminal value
- Excel modeling
- Sensitivity analysis
You do not need advanced mathematics to understand the core model. However, becoming proficient requires practice with financial statements, forecasting, accounting relationships, and valuation assumptions.
People Also Ask: What Is the Best Way to Learn DCF?
A practical learning sequence is more useful than memorizing formulas.
Start by building a simple five-year DCF for a familiar public company.
Then rebuild the same model using more detailed revenue and margin assumptions.
Courses can provide structured practice. For example, Coursera’s DCF modeling guided project is listed as an intermediate-level project designed to be completed in about two hours, while its DCF Valuation Modeling Fundamentals course was updated in May 2026.
CFI also offers a DCF curriculum covering valuation foundations, model construction, and sensitivity analysis.
For deeper valuation theory, Aswath Damodaran’s NYU materials include DCF lectures, datasets, and valuation exercises.
Learners who prefer a mobile interactive group format can also look for programs that combine short lessons with guided spreadsheet exercises and peer discussion.
Common DCF Training Mistakes
Beginners frequently make avoidable errors.
Using unrealistic growth: High growth should have a business explanation.
Mixing cash-flow definitions: Do not use FCFF with a cost of equity or FCFE with WACC without understanding the framework.
Ignoring working capital: Revenue growth can require additional investment in receivables and inventory.
Overstating terminal growth: A perpetual growth rate should be economically defensible.
Using inconsistent assumptions: Nominal cash flows generally require a nominal discount rate, while real cash flows require a real discount rate.
Skipping sensitivity analysis: A single DCF output can create false precision.
Confusing enterprise value with equity value: Debt and cash adjustments matter.
How to Practice DCF Training in Excel
Excel remains a useful environment for learning financial modeling because it makes the relationships between assumptions and outputs visible.
A clean training model can contain these sections:
Historical Data → Assumptions → Revenue Forecast → Income Statement → UFCF → Discount Factor → Terminal Value → Enterprise Value → Equity Value → Sensitivity Analysis
Use separate input cells for major assumptions.
Label historical figures and forecasts clearly.
Keep formulas consistent across years.
Avoid hard-coding numbers inside complex formulas.
CFI’s financial modeling guidance also emphasizes transparency, consistent labeling, layout, and model structure.
The objective is not merely to make Excel calculate. It is to make another analyst able to follow and review your logic.
Final Takeaway
Discounted cash flow training is ultimately about learning to connect business performance, cash generation, risk, and time.
A useful DCF does not claim to know the exact future value of a company. Instead, it provides a structured way to estimate value based on explicit assumptions.
In 2026, inflation remains above the Federal Reserve’s stated 2% goal, the federal funds target range is 3.75%–4.00%, and real GDP growth has moderated. Those conditions reinforce the importance of understanding how discount rates and operating assumptions affect valuation.
The next practical step is to build a five-year DCF in Excel for one U.S. public company. Forecast its revenue, margins, free cash flow, WACC, and terminal value. Then run sensitivity analysis and document every major assumption.
That process will teach you far more than memorizing a DCF formula.
Disclaimer
This article is provided for educational and informational purposes only and does not constitute financial, investment, tax, accounting, or legal advice. DCF valuations depend heavily on assumptions and estimates, and the results can differ substantially from actual market values. Consult a qualified financial professional for advice based on your individual circumstances.